Health Security Se National Security Cess (Second Amendment) Rules, 2026: Changes to Rule 35
Court / Authority
CBDT (Income Tax)
Update / Judgement Date
19 May 2026
Date of Publication
02 Nov 2026
Case No.
Notification No. 03/2026 – HSNS Cess
Source
WCP News Bulletin
Author
Pranjal Jha — WCP Legal Desk
Reading Time
3 min read
View Count
1
Introduction
The Ministry of Finance, Department of Revenue, issued Notification No. 03/2026 – HSNS Cess on 20 May 2026, introducing the Health Security Se National Security Cess (Second Amendment) Rules, 2026. Exercising its powers under Section 35 of the Health Security Se National Security Cess Act, 2025, the Central Government amended Rule 35 of the Health Security Se National Security Cess Rules, 2026. The amendments primarily concern the removal and modification of certain provisions relating to the administrative and accounting framework under the Rules.
Key amendments to Rule 35
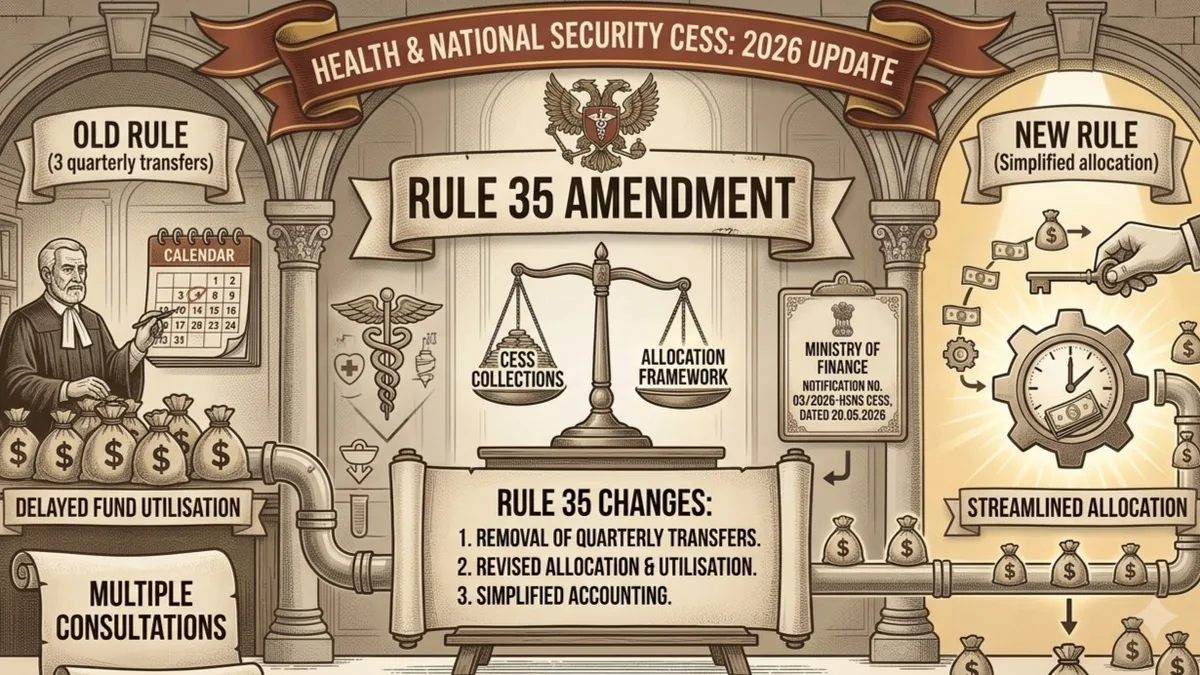
The notification introduces three changes to Rule 35:
- Omission of sub-rule (3): Sub-rule (3) of Rule 35 has been completely removed.
- Amendment to sub-rule (5): The words “Budget Division, Department of Economic Affairs in consultation with” have been omitted. This removes the specific reference to the Budget Division of the Department of Economic Affairs in the provision.
- Amendment to sub-rule (6): The existing reference to “the Principal Chief Controller of Accounts, Central Board of Indirect Taxes and Customs, and as approved by the Comptroller and Accountant General of India” has been replaced with “the Chief Controller of Accounts (Finance)”.
Commencement and applicability
The notification provides that the amended rules shall come into force from the date of their publication in the Official Gazette, that is, 20 May 2026. Accordingly, the changes take effect from that date.
Background of the amendment
The notification also records the legislative history of the principal rules. The Health Security Se National Security Cess Rules, 2026 were initially notified through Notification No. 01/2026 – HSNS Cess, dated 1 January 2026, and were subsequently amended through Notification No. 02/2026 – HSNS Cess, dated 30 January 2026. The present notification constitutes the second amendment to the Rules.
Significance of the amendment
- The amendment primarily modifies the administrative and accounting arrangements under Rule 35. It removes sub-rule (3), deletes a reference to the Budget Division of the Department of Economic Affairs from sub-rule (5), and revises the designated accounting authority under sub-rule (6) to the Chief Controller of Accounts (Finance).
- These changes indicate a revision in the institutional references and responsibilities specified under Rule 35. However, the notification does not explain the policy reasons behind these changes or provide details of their financial impact.
Conclusion
Notification No. 03/2026 – HSNS Cess introduces targeted amendments to Rule 35 of the Health Security Se National Security Cess Rules, 2026. Its principal effect is to remove one sub-rule and revise the references to the authorities involved in the administrative and accounting framework. The amendments came into force on 20 May 2026, upon publication in the Official Gazette.
Full Judgement / Attachment
Full Judgement
Frequently asked questions about CBDT (Income Tax)
- What is the CBDT?
- The Central Board of Direct Taxes is a statutory body under the Central Boards of Revenue Act, 1963, in the Department of Revenue, Ministry of Finance. It frames direct tax policy and administers the Income Tax Department.
- What changed with the Income-tax Act, 2025?
- The Income-tax Act, 2025 replaced the Income-tax Act, 1961 with effect from 1 April 2026. It replaces the 'previous year' and 'assessment year' with a single 'tax year'. Returns for income earned up to 31 March 2026 are still filed under the 1961 Act.
- Are CBDT circulars binding?
- CBDT circulars issued under the Act are binding on income-tax authorities, but not on taxpayers or the courts. A taxpayer can rely on a beneficial circular, while the courts interpret the law independently.
- How do I appeal against an income tax order?
- A first appeal against an assessment order lies to the Commissioner of Income-tax (Appeals) or the Joint Commissioner (Appeals). A further appeal lies to the Income Tax Appellate Tribunal, then to the High Court on a substantial question of law, and finally to the Supreme Court.
- How can White Collar Professional help with a CBDT or income tax matter?
- Post your requirement on White Collar Professional to receive proposals from verified Chartered Accountants and tax Advocates, compare them, and pay securely through the platform. This page also tracks the latest CBDT or income tax CBDT circulars and income tax updates as they are reported.