
Deciding two connected writ petitions arising from a common Industrial Tribunal Award, the Delhi High Court set aside the Tribunal's direction granting hotel workmen a further…
Labour Laws
06/09/20264 min read
Update / Judgement Date
14 Dec 2025
Source
WCP News Bulletin
Author
Sakshi Bhardwaj — WCP Legal Desk
Reading Time
4 min read
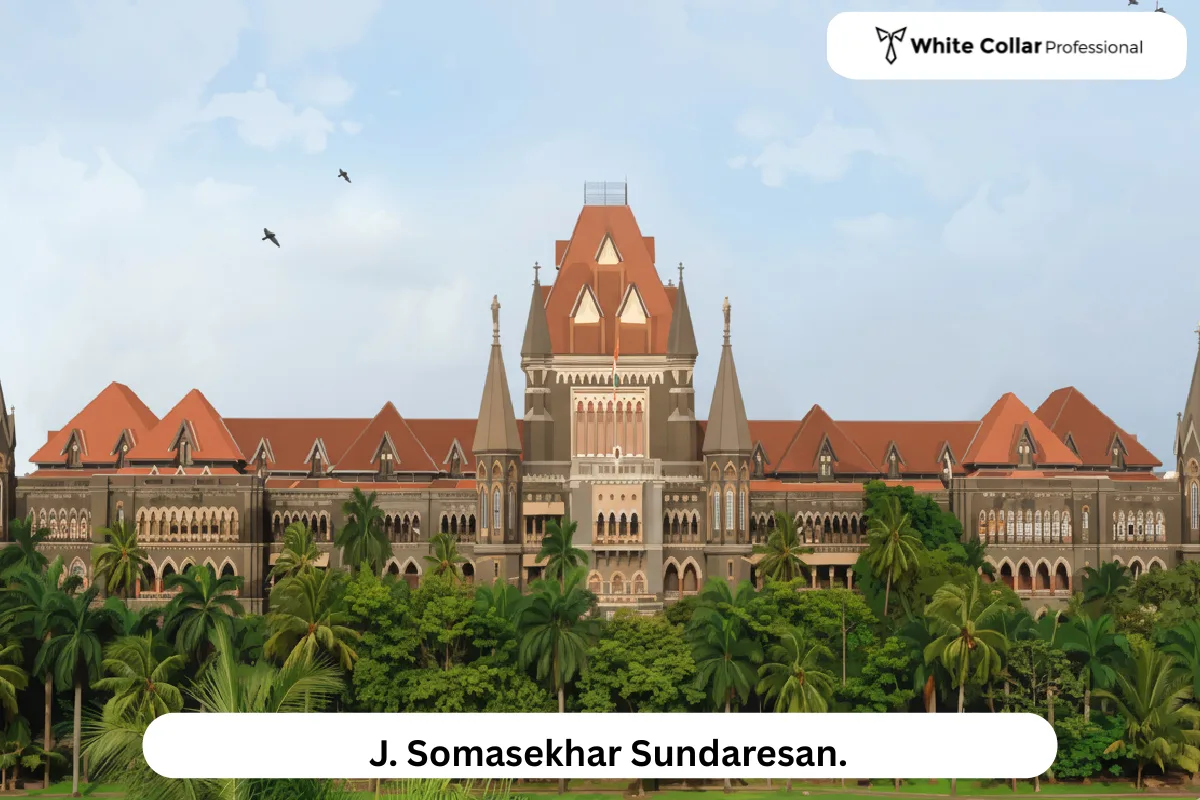
Headnote:
The Bombay High Court dismissed a writ petition filed by New India Assurance Co. Ltd. challenging an order of the National Consumer Disputes Redressal Commission (NCDRC) which directed the insurer to honour an insurance claim arising from the July 2005 Mumbai floods. The Court held that the insurer could not repudiate liability on the ground of dishonour of the premium cheque when the policy had already been renewed, the cheque was received before commencement of risk, and the alleged dishonour was not proved to be due to insufficiency of funds. The Court further held that the consumer complaint was not barred by limitation, as the insurer’s conduct showed continued processing of the claim well beyond the alleged date of repudiation.
Background:
The petitioner insurer issued a Standard Fire and Special Perils Policy to the respondent housing society for the period 25 July 2004 to 24 July 2005.
Prior to expiry, the Society paid the renewal premium of ₹18,910 by cheque on 17 July 2005, leading to issuance of a renewed policy on 22 July 2005 for the period 25 July 2005 to 24 July 2006.
On 26 July 2005, torrential rains in Mumbai caused extensive damage to the Society’s property, and a claim was lodged on 07 August 2005.
The insurer claimed that the premium cheque was dishonoured and that the policy stood cancelled on 04 August 2005.
The Society disputed this, and the bank confirmed that there were sufficient funds, and the cheque was not processed due to infrastructure failure caused by floods.
The State Consumer Commission awarded compensation of ₹5 lakh jointly against the insurer and the bank.
On appeal, the National Commission directed the insurer alone to pay ₹34,78,002.40, holding that repudiation was unjustified.
Aggrieved, the insurer filed the present writ petition.
Issues for Consideration
Whether the consumer complaint was barred by limitation under Section 24A of the Consumer Protection Act, 1986.
Whether the insurer could rely on Section 64VB of the Insurance Act, 1938 to deny liability due to alleged non-receipt of premium.
Whether the insurer’s conduct amounted to deficiency of service.
Court’s Observations:
Limitation is a mixed question of fact and law, and both the State Commission and National Commission had returned concurrent findings based on evidence.
The insurer’s conduct—particularly its letter dated 31 January 2006 chasing the surveyor and threatening regulatory action—clearly showed that the claim was being processed, contradicting the plea of repudiation on 04 August 2005.
The insurer failed to produce the cheque return memo or prove dishonour due to insufficiency of funds.
Under Section 64VB, receipt of the premium cheque before assumption of risk is sufficient; delay or mishandling of the cheque by the insurer cannot prejudice the insured.
The insurer’s failure to promptly present the cheque and to re-present it despite bank advice amounted to operational negligence.
The reliance on Kandimalla Raghavaiah and Yellamma was held to be misplaced, as the factual matrix demonstrated continuing cause of action and insurer-driven delay.
Decision:
The writ petition was dismissed.
The National Commission’s order directing payment of compensation was upheld.
The Court imposed costs of ₹25,000 on the insurer, payable to the Society.
The Court reaffirmed that consumer protection law must be interpreted pragmatically in favour of consumers, particularly where delay is attributable to the service provider.
Legal Provisions Discussed:
Section 24A, Consumer Protection Act, 1986 – Limitation period for filing consumer complaints.
Section 64VB, Insurance Act, 1938 – Assumption of risk only upon receipt of premium.
Doctrine of deficiency of service under consumer law.
Principles governing cause of action and continuing liability.
Case: New India Assurance Co. Ltd. v. Gayatridham Phase Co-op. Housing Society & Anr.
Court: High Court of Judicature at Bombay
(Civil Appellate Jurisdiction)
Coram: Justice Somasekhar Sundaresan
Writ Petition No. 12510 of 2024
Deciding two connected writ petitions arising from a common Industrial Tribunal Award, the Delhi High Court set aside the Tribunal's direction granting hotel workmen a further…

Headnote The Delhi High Court dismissed a prosecutrix's appeal against acquittal of the accused on charges under Sections 328/376 2 n /377/506/509 IPC, despite DNA evidence…

Fathimath Thasneem V.K. v. Union of India and Others | High Court of Kerala at Ernakulam | 3rd September, 2026 A habeas corpus writ petition by the wife of a detenu challenging…

Thasmitha Abukutty v. State of Kerala and Others | High Court of Kerala at Ernakulam | 2nd September, 2026 A writ petition by the wife of a preventive detenu challenging a…

Brahm Kishore Dixit v. The State of Madhya Pradesh and Others | High Court of Madhya Pradesh, Gwalior | 1st September, 2026 A writ petition under Article 226 by a police Assistant…

Anil Kumar Patel v. Smt. Munni Bai Barman and Others | High Court of Madhya Pradesh, Jabalpur | 1st September, 2026 A Motor Vehicle Act appeal under Section 173 1 against a Claims…

M/s. Kuber Mutual Benefits Ltd. & Ors. v. The State of Maharashtra & Ors. | High Court of Judicature at Bombay Appellate Side | 3rd September, 2026 A Court Receiver's Report…

The Municipal Corporation of Greater Bombay v. M/s. Atul Raj Builders Pvt. Ltd. | High Court of Judicature at Bombay Ordinary Original Civil Jurisdiction | 3rd September, 2026 A…

Devender Yadav & Anr. v. Election Commission of India & Anr. | High Court of Delhi Single Judge | Decided on: 03.09.2026 In a challenge to the Election Commission of India's…

Brij Sharadbhai Bhatt & Ors. v. National Medical Commission & Ors. | High Court of Delhi Division Bench | Decided on: 03.09.2026 The Delhi High Court dismissed a challenge by…