Delhi ITAT on Section 153C: Seized Documents Must Belong/Pertain to Assessee.
Update / Judgement Date
18 Nov 2025
Source
WCP News Bulletin
Author
Sakshi Bhardwaj — WCP Legal Desk
Reading Time
4 min read
View Count
2
Other Legal MattersFinancial Management
WCP News Bulletin
Headnote:
The Delhi ITAT partly allowed the Revenue’s appeal, confirming that additions under Section 153C of the Income Tax Act can only be made if the seized documents “belong to,” “pertain to,” or “contain information relating to” the assessee. The Tribunal observed that the AO’s satisfaction note incorrectly attributed transactions to the assessee, whereas the documents were actually owned and reported by the Antriksh Group of Companies. Consequently, the additions made on the basis of such documents were rightly deleted by the CIT(A), except to the extent of the retrospective applicability of the amended Section 153C.
Background:
A search and seizure action under Section 132 was conducted on the Antriksh Group on 05.02.2014. During the search, a ledger (Page 19 of Annexure A-3) was seized from Rakesh Kumar Yadav’s residence. The AO alleged this document pertained to Planet Infra Promoters Pvt. Ltd. (assessee).
The AO recorded a satisfaction note dated 02.03.2016 and issued notice under Section 153C for AY 2013-14, treating Rs. 75 lakhs in the seized document as unexplained income of the assessee.
The assessee challenged the additions before the CIT(A), which held that the seized document did not “belong to” the assessee and therefore deleted the additions.
Revenue’s Contentions:
The Revenue argued that Section 153C, amended by Finance Act 2015, replaced “belongs to” with “pertains to or relates to,” broadening its scope.
It contended that the satisfaction note by AO clearly linked the seized ledger to the assessee’s transactions, and that the letter dated 16.06.2014, allegedly filed by the assessee, corroborated the nexus.
Assessee’s Contentions
The assessee argued that the seized document mentioned only “Received from Ajit Rs. 75 lakhs,” with no reference to the assessee company.
The letter relied upon by AO was filed by the Antriksh Group, not the assessee, and all transactions therein pertained to Antriksh Group companies.
The assessee relied on Tribunal precedents (DCIT vs. Shri Jethmal Mehta, ITA Nos. 8985–8987/Del/2019) where similar seized documents from Rakesh Kumar Yadav were held not to relate to the respective assessee.
Tribunal’s Observations:
The Tribunal noted that the seized ledger contained no mention of the assessee’s name; it was a transaction solely between Rakesh Kumar Yadav and Ajit Singh.
The satisfaction note failed to establish a clear nexus between the seized document and the assessee or quantify its impact on the assessee’s income.
Reliance on the letter dated 16.06.2014 was misplaced as it was filed by Antriksh Group companies.
The Tribunal reaffirmed the principle that mere assumptions based on surnames (e.g., “Mehta”) cannot establish ownership or relevance of documents to the assessee.
While acknowledging the retrospective applicability of Section 153C (post Finance Act 2015), the Tribunal confirmed that the AO’s satisfaction note was factually incorrect in linking the seized documents to the assessee.
Decision:
The Revenue’s appeal was partly allowed: the Tribunal upheld the retrospective applicability of the amended Section 153C but confirmed the CIT(A)’s deletion of additions, as the documents did not belong, pertain, or relate to the assessee.
Observations of the CIT(A) regarding lack of evidence linking the documents to the assessee were accepted.
Order Pronounced: 19 November 2025
Members:
Shri Brajesh Kumar Singh, Accountant Member
Shri C.N. Prasad, Judicial Member
Legal Provisions Discussed:
Section 153C, Income Tax Act, 1961 – Assessment based on documents seized from another person.
Section 132, Income Tax Act, 1961 – Search and seizure.
Section 292C, Income Tax Act, 1961 – Presumption regarding ownership of documents.
Finance Act 2015 – Amendment to Section 153C substituting “belongs to” with “pertains to or relates to.”
Citation: ITA No. 8988/Del/2019
Case: DCIT, Central Circle-1, Gurgaon v. Planet Infra Promoters Pvt. Ltd.
Tribunal: Income Tax Appellate Tribunal, Delhi Bench “F”, New Delhi
Coram: Shri Challa Nagendra Prasad, Judicial Member & Shri Brajesh Kumar Singh, Accountant Member
The Division Bench dismissed the connected writ appeals, while making a limited modification to the Single Judge’s findings concerning the Bar Council of Kerala. In light of…
The High Court held that the trial court was not justified in directing the parties to undergo fresh DNA testing when the existing expert report had not been rejected for legally…
The High Court held that a subsequently communicated minimum 20% local-content requirement, including an indigenously developed EMS software condition, could not be…
The Division Bench held that the petitioner had been deprived of a reasonable opportunity to present its case before the Commissioner of Sales Tax. An adjournment request must be…
The High Court exercised its inherent jurisdiction to quash a POCSO FIR and the pending trial after obtaining independent reports verifying the parties’ marriage, family…
The Division Bench held that the writ court had exceeded the proper scope of the dispute between the supplier and KSBCL by deciding, in effect, the Revenue’s separate tax…
The High Court considered the petitioners’ request for regular bail in an Enforcement Directorate prosecution alleging money laundering under the Prevention of Money Laundering…
The High Court upheld the appellant’s conviction under Section 18 c of the NDPS Act for possession of opium but reduced the sentence of seven years’ rigorous imprisonment to the…
The High Court dismissed the State’s appeal against acquittal, holding that the trial court’s view was a reasonably possible view on the evidence and that material inconsistencies…
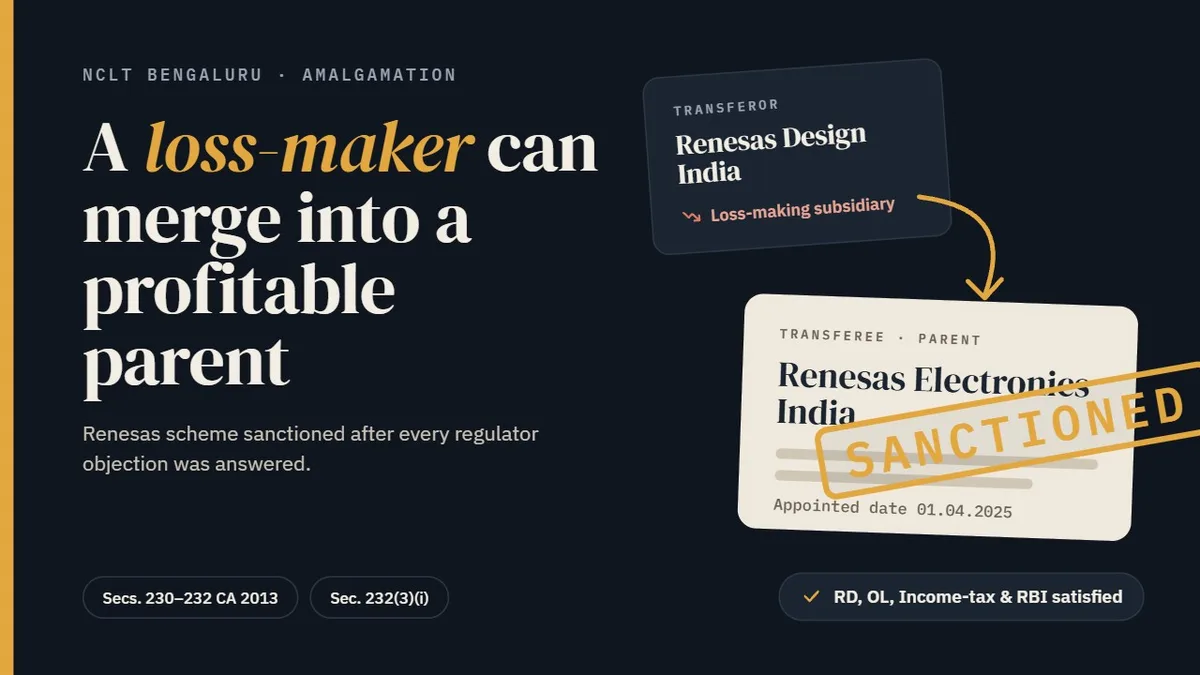
Renesas Design India Pvt. Ltd., a loss-making wholly owned subsidiary engaged in semiconductor design, and its parent Renesas Electronics India Pvt. Ltd. sought sanction of a…