The Division Bench dismissed the connected writ appeals, while making a limited modification to the Single Judge’s findings concerning the Bar Council of Kerala. In light of…
Civil LawOther Legal Matters
21/11/20265 min read
Update / Judgement Date
03 Nov 2025
Source
Author
Team — WCP Legal Desk
Reading Time
1 min read
View Count
2
The Income Tax Appellate Tribunal (ITAT) held that in the absence of credible evidence for transport expenditure claimed by a taxpayer, the Assessing Officer (AO) was justified in applying the presumptive income scheme under Section 44AD and estimating income at 8%. The decision emphasises that inadequate documentation or failure to substantiate claimed expenses can trigger statutory presumptions and restrict expense deduction claims. Taxpayers engaged in presumptive business income should maintain clear books, substantiation for outlays and evidentiary backing for claims to avoid automatic estimation under the provisions.
© 2026 White Collar Professional Technologies Pvt. Ltd. All rights reserved. CIN: U74999MH2024PTC000001
The Division Bench dismissed the connected writ appeals, while making a limited modification to the Single Judge’s findings concerning the Bar Council of Kerala. In light of…
The High Court held that the trial court was not justified in directing the parties to undergo fresh DNA testing when the existing expert report had not been rejected for legally…
The High Court held that a subsequently communicated minimum 20% local-content requirement, including an indigenously developed EMS software condition, could not be…
The Division Bench held that the petitioner had been deprived of a reasonable opportunity to present its case before the Commissioner of Sales Tax. An adjournment request must be…
The High Court exercised its inherent jurisdiction to quash a POCSO FIR and the pending trial after obtaining independent reports verifying the parties’ marriage, family…
The Division Bench held that the writ court had exceeded the proper scope of the dispute between the supplier and KSBCL by deciding, in effect, the Revenue’s separate tax…
The High Court considered the petitioners’ request for regular bail in an Enforcement Directorate prosecution alleging money laundering under the Prevention of Money Laundering…
The High Court upheld the appellant’s conviction under Section 18 c of the NDPS Act for possession of opium but reduced the sentence of seven years’ rigorous imprisonment to the…
The High Court dismissed the State’s appeal against acquittal, holding that the trial court’s view was a reasonably possible view on the evidence and that material inconsistencies…
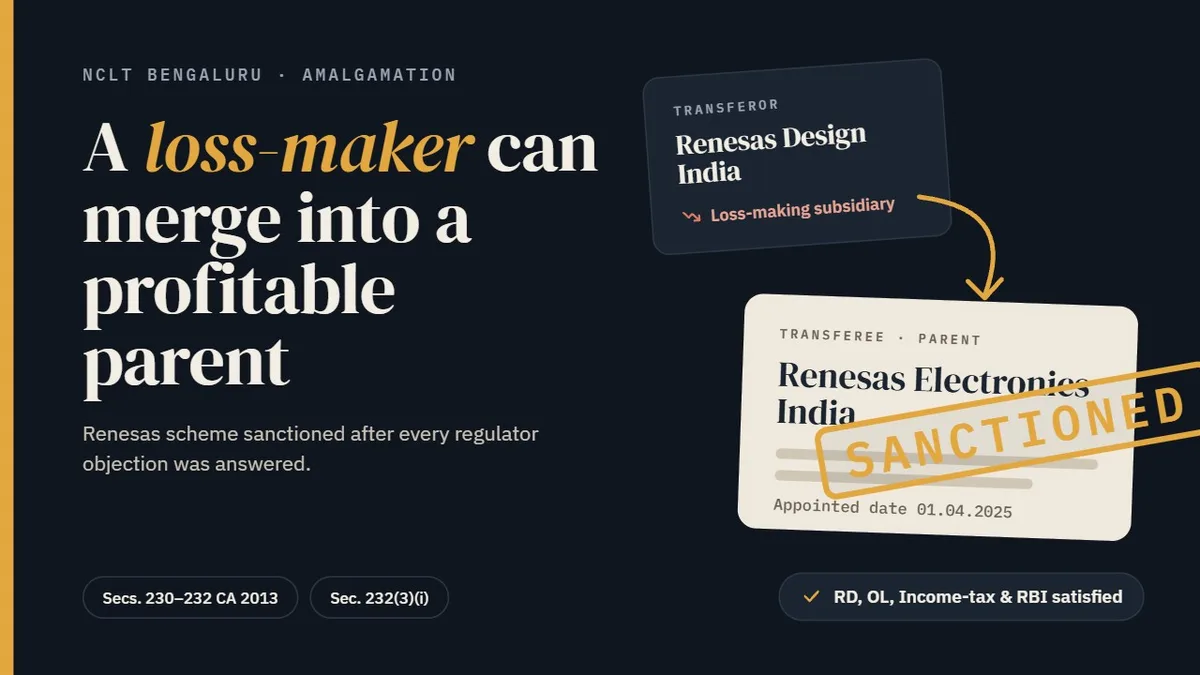
Renesas Design India Pvt. Ltd., a loss-making wholly owned subsidiary engaged in semiconductor design, and its parent Renesas Electronics India Pvt. Ltd. sought sanction of a…