The Supreme Court clarified the temporal operation of its 11 March 2026 judgment on OBC creamy-layer status. It declined to reopen selections, appointments or seniority already…
Civil Law
Court / Authority
Indirect Taxes and Customs (CBIC)
Update / Judgement Date
03 Nov 2026
Case No.
Customs Appeal No. 60160 of 2026
Author
Arshee Saifi — WCP Legal Desk
Reading Time
7 min read
View Count
6
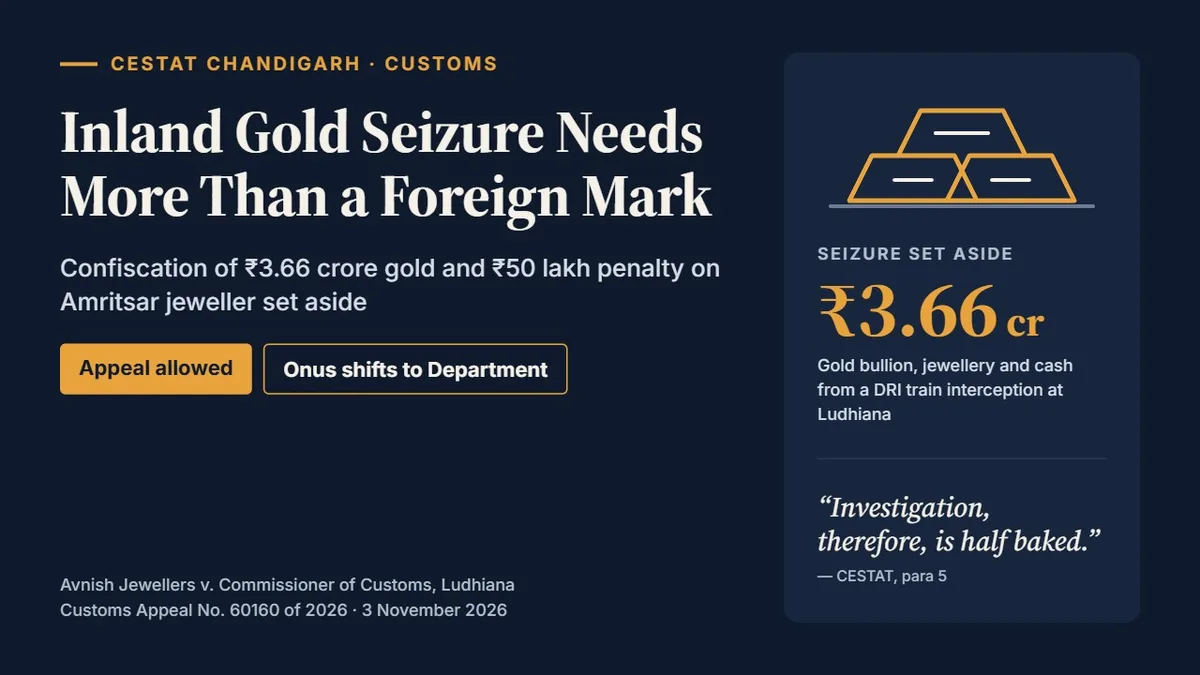
Key Proposition: In an inland seizure of gold not made at a port or border, where the possessor produces invoices, books of account and supplier statements showing domestic procurement, the onus shifts back to the Department, and confiscation cannot rest on an untested foreign-looking mark on a single cut piece without proof of 999.9 purity or a trail to an import.
A. Background / Synopsis :
The appellant has run a jewellery shop at Amritsar since July 2003, making nose pins (nath) and ear rings (walian), and is GST-registered. (Para 1.1)
13.06.2024: intercepted on Train No. 13005 at Ludhiana; luggage held 1,558 g of bullion cut pieces, nose pins and ear rings (gross 5,610 g) and ₹7,70,000 in cash, all seized on 14.06.2024. (Paras 1.2–1.3)
DRI searched his Amritsar shop on 14.06.2024 and 19.06.2024 and found no stock variation; that stock was not seized. (Para 1.13)
Show cause notice dated 20.11.2024 → Order-in-Original dated 30.09.2025 (Joint Commissioner, Ludhiana): absolute confiscation of the bullion, jewellery (₹2,54,82,600) and cash, and a ₹50 lakh penalty → Order-in-Appeal dated 24.04.2026 upheld it. (Paras 1.4–1.6)
B. Issues For Consideration :
Full Judgement / Attachment
Full Judgement
C.Submissions Of Parties :
Appellant:
The bullion was bought against GST invoices from Ansh Jewellers, Amritsar and Shri Ji Traders, Lucknow, and from Navneet Lal Bal Krishna Jewellers, Lucknow (against a sale of nose pins); genuineness was never disputed and no notice went to the suppliers. (Paras 1.7, 1.20)
Pieces bore Indian marks (ABH, BR, JP, Aqua); the valuer did not separate purities or count pieces; the 'SAM' piece was never shown to be 999.9 pure. (Paras 1.8–1.10)
No reasonable belief existed, so Section 123 could not shift the burden; Sections 111(d), (l) and (m) do not apply without an import; cash is not a notified item. (Paras 1.14–1.21)
Relied on Gian Mahtani (SC), Akbar Badruddin Jiwani (SC) and Manisha Devi Jain (CESTAT). (Paras 1.19, 1.21)
Respondent (Revenue):
The appellant admitted carrying bullion; the 'SAM TM' marking, cut pieces in taped and newspaper packets, cash hidden in the bag and the absence of documents justified the belief. (Para 2.9)
Post-seizure stock reconciliation is not proof; Section 123(2) covers gold and its manufactures wherever seized; gold imported in breach of conditions is 'prohibited goods'. (Paras 2.6, 2.10–2.11)
Relied on Premal Ketan Radia (Cal HC) and D. Bhoormull (SC): the Department need not prove its case with mathematical precision. (Para 2.9)
D. Court's Observations & Analysis :
The goods were seized in transit; invoices and supplier names were given during investigation, and the Department cannot call them later interpolations when it delayed follow-up searches. (Para 3)
The valuer treated all bullion as one purity; ABH, BR, JP and Aqua are Indian marks; the 'SAM' cut piece had no purity test or biscuit number. (Paras 3–4)
Since 1993 gold bullion is restricted rather than prohibited, so in a town seizure invoices and book entries deserve credence and more evidence is needed than at a port or border. (Para 3)
Indian manufacturers now also make 99.9% gold, and for jewellery no presumption of foreign origin arises in an inland seizure. (Para 4)
Held: the Department failed to discharge even the initial burden of showing the goods were smuggled. (Para 4)
The same kinds of stock at the shop were accepted as genuine, so treating goods in transit differently shows 'double standards'. (Para 4)
Supplier statements recorded at Lucknow showed local purchases; the onus shifted to the Department, which did not trace the gold to any Bill of Entry. (Paras 4–5)
Held: the investigation was 'half baked' and, even on preponderance of probability, the Department's case fails. (Para 5)
Nothing links the jewellery or the cash to smuggled gold; how a traveller keeps cash is his prerogative. (Paras 3–4)
Held: seizure vacated; confiscation and penalty cannot survive. (Paras 4–5)
Notable Observations: “This points to the double standards of the department” (Para 4); “Investigation, therefore, is half baked.” (Para 5)
E. Decision & Directions :
F. Legal Provisions Discussed & Precedents Cited :
G. Case Details :
Disclaimer: This summary is an editorial aid and does not form part of the judgment. Refer to the original judgment before citing.
© 2026 White Collar Professional Technologies Pvt. Ltd. All rights reserved. CIN: U74999MH2024PTC000001
The Supreme Court clarified the temporal operation of its 11 March 2026 judgment on OBC creamy-layer status. It declined to reopen selections, appointments or seniority already…
The Supreme Court upheld the Delhi High Court Full Bench decision that the National Book Trust, India is an instrumentality of the State under Article 12 of the Constitution. The…
The Supreme Court issued further directions in the continuing proceedings concerning encroachments and ecological restoration in the Agasthyamalai landscape of Tamil Nadu. It…
The Supreme Court issued final directions to implement Himachal Pradesh’s entitlement to power from the Bhakra-Nangal and Beas hydro-electric projects. It fixed energy arrears at…
The Securities and Exchange Board of India SEBI has modified the threshold limits for taking unhedged positions in foreign exchange currency derivative contracts involving the…
Registration & Launch of AIF Schemes ● Standardized Private Placement Memorandum PPM : Mandatory adherence to templated disclosures for Category I, II, and III AIFs, ensuring…
The Reserve Bank of India has introduced strict regulatory measures for the foreign exchange market to enhance discipline and risk management. Under the new directions issued via…
The petitioner dental college challenged the Registrar’s order rejecting continuation of its affiliation for the academic year 2026–27. The High Court held that, under the Kerala…
The High Court of Karnataka dismissed the appeal filed by the Karnataka State Road Transport Corporation KSRTC challenging its liability and partly allowed the appeal filed by the…
The Supreme Court upheld the compulsory retirement of two Assistant Grade-III employees of the Chhattisgarh Legal Metrology Department. It found that the State had reviewed their…