The Division Bench dismissed the connected writ appeals, while making a limited modification to the Single Judge’s findings concerning the Bar Council of Kerala. In light of…
Civil Law
Court / Authority
NCLT & NCLAT
Update / Judgement Date
20 Nov 2026
Source
WCP News Bulletin
Author
Arshee Saifi — WCP Legal Desk
Reading Time
7 min read
View Count
1
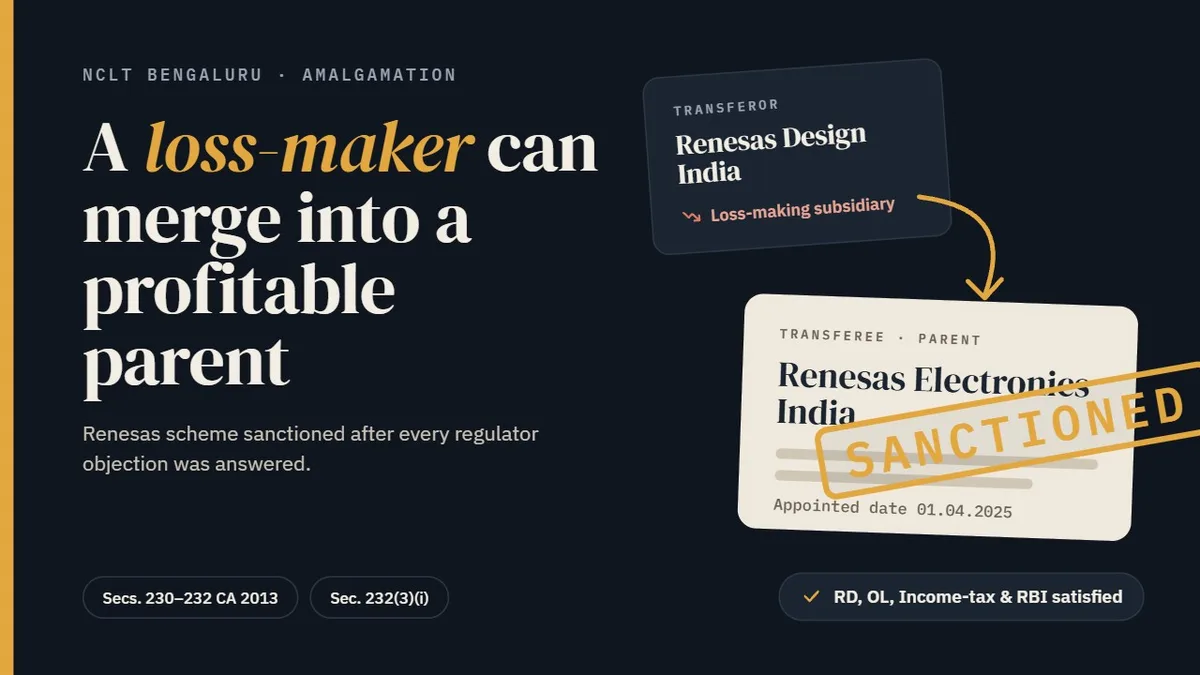
Key Proposition: Sections 230–232 of the Companies Act, 2013 do not bar a loss-making company from merging into a profitable one; where the Boards approve the scheme in their commercial wisdom and every statutory authority's observation is met by an explanation or a binding undertaking, the Tribunal may sanction the scheme, but the sanction grants no exemption from stamp duty, tax or any other liability.
Background / Synopsis :
The second-motion petition was filed on 24.02.2026; on the first-motion application, C.A. (CAA) No. 48/BB/2025, the meetings of all classes of shareholders and the unsecured creditors of both companies were dispensed with (Paras 1–2).
On 27.02.2026 notice issued under Section 230(5) and Rule 8 to the Regional Director, RoC, Official Liquidator, Income-tax authority and sectoral regulators, with publication in English and Kannada newspapers; service was proved by affidavit dated 30.04.2026 (Paras 3–4).
The transferor is wholly owned by the transferee, so no shares are issued as consideration and the transferor's shares stand cancelled (Para 12(e), Scheme Clause 8).
Full Judgement / Attachment
Full Judgement
© 2026 White Collar Professional Technologies Pvt. Ltd. All rights reserved. CIN: U74999MH2024PTC000001
Board resolutions of 05.11.2025, the statutory auditor's certificate under Section 133 on the accounting treatment (Clause 9), and affidavits stating there are no sectoral regulators, no debt restructuring and no pending investigations were filed (Paras 6–8).
Issues For Consideration :
Submissions Of Parties :
Show compliance with Section 90 (BEN-1/BEN-2) for the holding companies (Para 11(4)).
Justify merging a loss-making transferor into a profitable transferee (Para 11(6)).
Clause 12.1 clubbing of authorised capital is not in line with Section 232(3)(i); pay the fee difference (Para 11(7)).
Undertakings on statutory dues (Rs. 55,41,950 and Rs. 1,724.84 lakh), MSME dues (Rs. 70,170), FEMA/RBI compliance, employees and ESOPs, object clause, accounting treatment and Section 239; Section 240 liability continues (Paras 11(8)–(16)).
BEN-1/BEN-2 do not apply because no individual holds a majority in the parent; the parent will answer for any past non-compliance of the subsidiary (Para 11.1(a)).
Sections 230–232 do not restrict a profit-making and loss-making merger; the Boards approved it in their commercial wisdom (Para 11.1(b)).
Undertakings to pay the differential authorised-capital fee, clear statutory and MSME dues, protect employees under Clause 5, preserve the transferor's books and pay any tax demands that crystallise; ESOPs continue unchanged; both companies are in semiconductors, so no object-clause change is needed (Paras 11.1(c)–(l), 13.1).
Official Liquidator, Income-tax Department and RBI:
OL: the transferor is a going concern (revenue Rs. 45.88 crore in FY 2023-24 and Rs. 52.45 crore in FY 2024-25); MSME dues to be settled; employee terms preserved (Para 12).
RBI: companies must comply with FEMA themselves; the RBI does not vet individual schemes, so as not to preclude later action (Para 14).
Court's Observations & Analysis :
Decision & Directions :
Legal Provisions Discussed & Precedents Cited :
Case Details :
Disclaimer: This summary is an editorial aid and does not form part of the judgment. Refer to the original judgment before citing.
The Division Bench dismissed the connected writ appeals, while making a limited modification to the Single Judge’s findings concerning the Bar Council of Kerala. In light of…
The High Court held that the trial court was not justified in directing the parties to undergo fresh DNA testing when the existing expert report had not been rejected for legally…
The High Court held that a subsequently communicated minimum 20% local-content requirement, including an indigenously developed EMS software condition, could not be…
The Division Bench held that the petitioner had been deprived of a reasonable opportunity to present its case before the Commissioner of Sales Tax. An adjournment request must be…
The High Court exercised its inherent jurisdiction to quash a POCSO FIR and the pending trial after obtaining independent reports verifying the parties’ marriage, family…
The Division Bench held that the writ court had exceeded the proper scope of the dispute between the supplier and KSBCL by deciding, in effect, the Revenue’s separate tax…
The High Court considered the petitioners’ request for regular bail in an Enforcement Directorate prosecution alleging money laundering under the Prevention of Money Laundering…
The High Court upheld the appellant’s conviction under Section 18 c of the NDPS Act for possession of opium but reduced the sentence of seven years’ rigorous imprisonment to the…
The High Court dismissed the State’s appeal against acquittal, holding that the trial court’s view was a reasonably possible view on the evidence and that material inconsistencies…
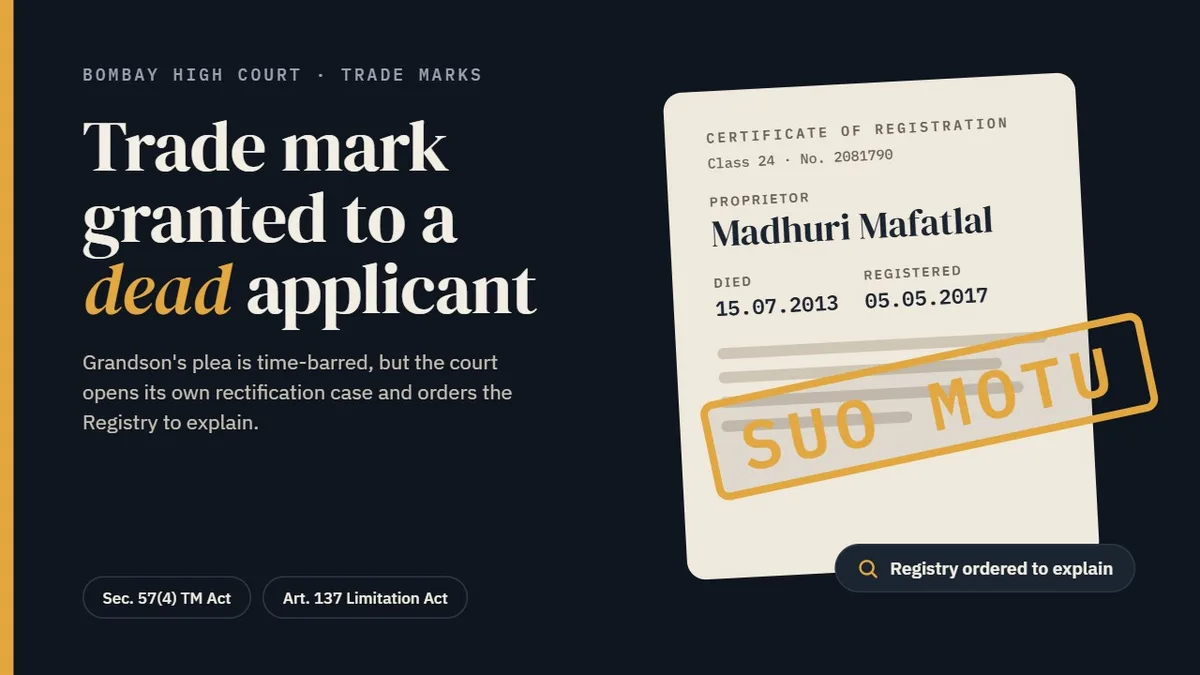
Varun Mafatlal, grandson of Madhuri Mafatlal, sought rectification under Section 57 of the Trade Marks Act, 1999 of entries recording his aunt Malavika Taktawala July 2018 and…