The Supreme Court dismissed the husband’s appeals and upheld the enhancement of interim maintenance payable to his wife from ₹75,000 to ₹1,50,000 per month. The Court found the…
Family Law
Court / Authority
Indirect Taxes and Customs (CBIC)
Update / Judgement Date
12 Nov 2026
Source
WCP News Bulletin
Author
Arshee Saifi — WCP Legal Desk
Reading Time
7 min read
View Count
4
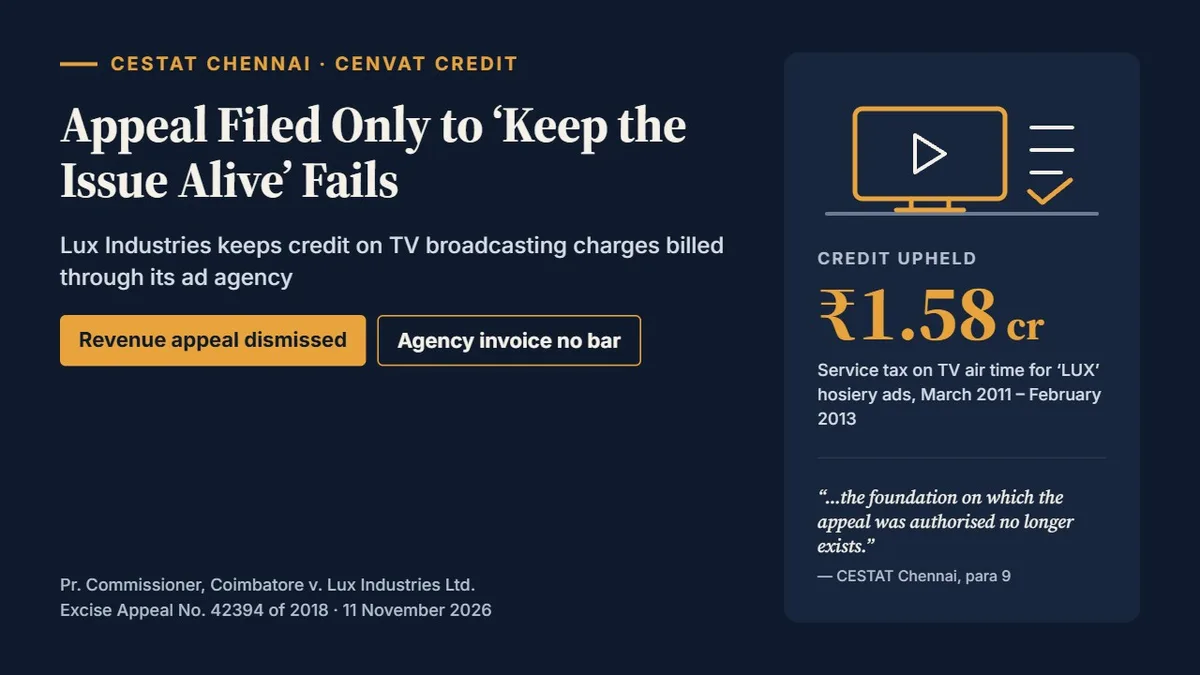
Key Proposition: Service tax charged by TV channels on broadcasting an advertiser's commercials is CENVAT credit of the advertiser even though the channels invoiced the advertising agency, where the agency only passed the charges and tax through as reimbursement; and a Revenue appeal authorised solely to 'keep the issue alive' pending another case cannot survive once that case is decided against the Revenue.
A. Background / Synopsis :
B. Issues For Consideration :
Full Judgement / Attachment
Full Judgement
© 2026 White Collar Professional Technologies Pvt. Ltd. All rights reserved. CIN: U74999MH2024PTC000001
C. Submissions Of Parties :
The broadcasting service was received by Prachar, since the channels invoiced Prachar alone; it was Prachar's input service and Prachar paid tax only on its commission. (Para 5)
Rules 3 and 9 of the CCR and Rule 4A of the Service Tax Rules were contravened, and Rule 9(2) cannot condone credit on invoices not issued by the service provider. (Para 5)
The Order-in-Appeal was not proper because the Department had appealed against Zapak Digital Entertainment (relying on Union of India v. West Coast Paper Mills). (Para 5)
The Committee of Commissioners accepted the Order-in-Appeal on merits; the Zapak appeal has since been dismissed, and Indian Oil Corporation was never challenged. (Para 6)
Having allowed credit on Prachar's commission for procuring the broadcasting, the Department cannot say the respondent did not receive that service; reliance on Shivraj Cable Network and Power Soap. (Para 6)
D. Court's Observations & Analysis :
The review order shows both Committee members agreed the Order-in-Appeal deserved acceptance on merits; the appeal was filed only to keep the issue alive as a matter of judicial discipline. (Paras 8–9)
The Department's appeal in Zapak Digital Entertainment was dismissed by the Bombay High Court (2018 (18) GSTL 583 (Bom)), so West Coast Paper Mills no longer helps the Revenue. (Para 10)
Indian Oil Corporation, an independent basis of the Order-in-Appeal, stands unchallenged and is by itself sufficient to sustain it. (Para 11)
Both decisions were followed in Kellogg India and Power Soap; the Madras High Court dismissed the Revenue's appeal in Power Soap on the very same questions (C.M.A. No. 3137 of 2018, 03.01.2019). (Para 12)
Prachar neither paid tax on the broadcasting charges as part of its output nor took credit on them; under Board Circular dated 31.10.1996, such charges are not part of an agency's taxable value, so reimbursement through the agency's invoice was the only way the tax could reach the advertiser. (Para 14)
Lux commissioned the advertisements of its own products, paid for the broadcast and the tax, and used the service in its manufacture; advertisement is expressly within 'input service' under Rule 2(l). (Para 15)
Allowing credit on the commission while denying it on the broadcast the commission procured is internally inconsistent. (Para 16)
Prachar's invoices carry the particulars Rule 9(2) requires, and there is no risk of double credit since Prachar did not take it (Shivraj Cable Network followed). (Para 17)
Held: the appeal fails on its own record and on merits; the plea on limitation need not be examined. (Para 18)
Notable Observations: “It is enough that the foundation on which the appeal was authorised no longer exists.” (Para 9); “Both components arise from a single transaction.” (Para 16)
E. Decision & Directions :
1. Revenue's appeal dismissed; Order-in-Appeal No. CMB-CEX-000-APP-175-18 dated 20.07.2018 upheld. (Para 19)
2. Respondent entitled to consequential relief, if any, in accordance with law. (Para 19)
Costs: Not stated in judgment.
Separate Opinions: None.
F. Legal Provisions Discussed & Precedents Cited :
G. Case Details :
Disclaimer: This summary is an editorial aid and does not form part of the judgment. Refer to the original judgment before citing.
The Supreme Court dismissed the husband’s appeals and upheld the enhancement of interim maintenance payable to his wife from ₹75,000 to ₹1,50,000 per month. The Court found the…
The Supreme Court allowed the appeal of a woman who suffered severe electrocution injuries, resulting in amputation of her right hand and permanent disability. It set aside the…
The Supreme Court dismissed the Delhi Development Authority’s appeals and upheld directions requiring release of gratuity to two retired employees who had been honourably…
The Supreme Court dismissed the challenge by candidates to the recruitment process for Excise Constables in Nagaland. It held that the recruitment was governed by the Nagaland…
The Supreme Court dismissed the State of Kerala’s appeal against a finding that 12 acres of land in Edakkara Village, Malappuram District, did not constitute private forest and…
The Supreme Court allowed the Union of India’s transfer petitions and directed that two cases registered in Jammu and Kashmir and Haryana be transferred to the NIA Special Court…
The Supreme Court examined the termination of an Associate Professor during probation at the Indian Institute of Science, Bengaluru. The central question was whether a termination…
The Supreme Court considered a batch of appeals arising from the insolvency resolution processes of Videocon Industries Limited VIL , twelve other Videocon group companies and…
A joint venture formed by two companies was a partnership on the substance of its agreement, including the project business, profit-sharing and mutual agency; because the…
Although no fundamental right exists to carry on the liquor trade, the State cannot keep temporary licences suspended beyond the election period without disclosing cogent reasons…