Lease Premium for Factory Land Is an Input Service Despite 2011 Deletion of 'Setting Up': CESTAT Chennai Restores ₹2.32 Crore CENVAT Credit, Sets Aside Equal Penalty
Court / Authority
Indirect Taxes and Customs (CBIC)
Update / Judgement Date
04 Nov 2026
Case No.
Excise Appeal No. 41410 of 2018 (Final Order No. 41164/2026)
Source
execise, tax and customs
Author
Arshee Saifi — WCP Legal Desk
Reading Time
9 min read
View Count
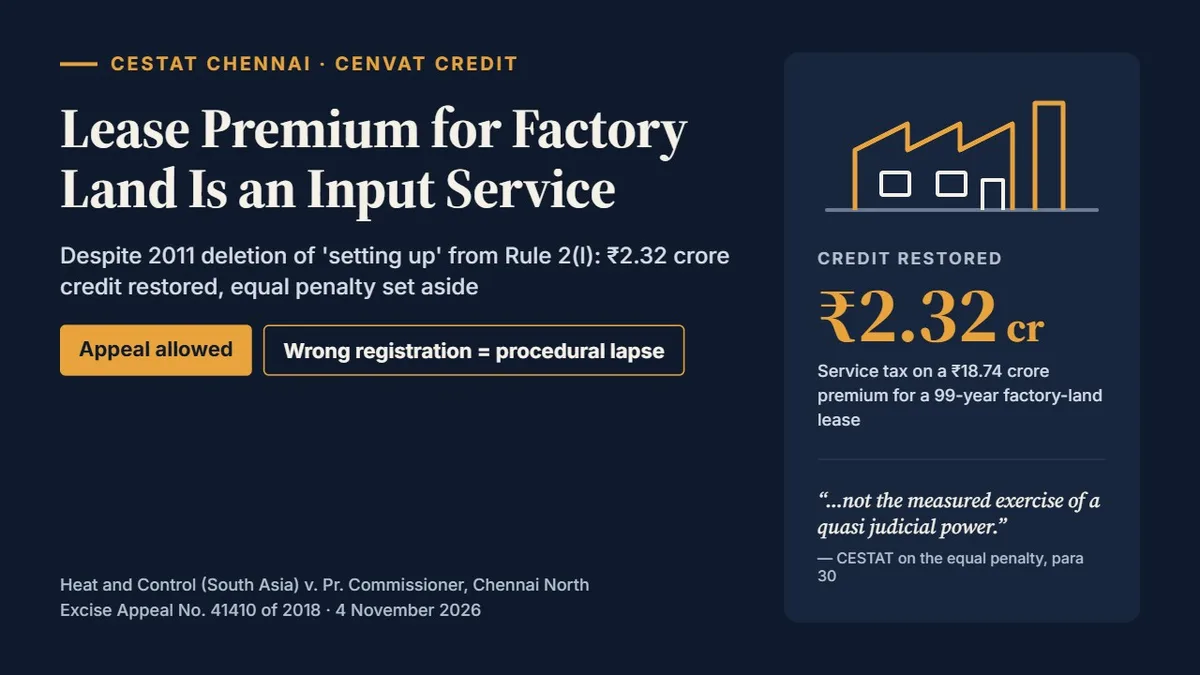
Key Proposition: Service tax paid on a lease premium for land on which a manufacturer sets up its factory is credit on an input service under the main limb of Rule 2(l) of the CENVAT Credit Rules, 2004, notwithstanding the 2011 deletion of 'setting up' from its inclusive part; and an admissible credit is not 'taken wrongly' under Rule 14 merely because it was first entered in another registration of the same legal person.
A. Background/synopsis:
- The appellant makes food-processing equipment at Guindy and renders erection, commissioning and allied services from its Anna Nagar service-tax registration; its input service distributor listing there was omitted from 14.12.2013. (Paras 1–2)
- 31.12.2013: 99-year lease of 8.33 acres at Mahindra World City for ₹18,74,25,000; the lessor charged ₹2,31,65,730 service tax under renting of immovable property on an invoice addressed to Anna Nagar. (Para 3)
- July 2014: credit taken at Anna Nagar and shown in the revised ST-3 return of 14.01.2015 as 'on acquisition of long term lease land'; factory registered on 20.06.2016; credit reversed at Anna Nagar and taken in the factory's ER-1 return for March 2017. (Paras 4, 12)
- Audit → show cause notice dated 10.04.2017 → Order-in-Original No. 29/2018 dated 12.03.2018 confirming the demand with interest and an equal penalty under Rule 15(3) read with Section 78; proposed Section 78A penalty on the Director (Taxation) dropped. (Paras 5–8)
B. Issues For Consideration :
- Whether the order is void for being passed beyond six months from the notice, contrary to Section 73(4B)(a).
- Whether service tax on the lease premium is on an input service under Rule 2(l) as it stood after 01.04.2011.
- Whether the credit is recoverable because it was taken in the Anna Nagar registration and not the factory's account.
- Whether interest and penalty are sustainable.
C. Submissions Of Parties :
- Appellant:
The main limb of Rule 2(l) covers services used directly or indirectly in relation to manufacture; deleting 'setting up' does not exclude them (Shell India, Komatsu India, Nemak Aluminium; on lease premium, Zuari Cement and Kellogs India). (Para 9)
Registration is not a condition for credit; liability rests on the legal entity; missing ISD registration is a curable lapse (mPortal, Rakindo Kovai, Dashion, Pricol, Circular No. 1063/2/2018-CX). (Para 10)
The order, passed eleven months after the notice, breaches Section 73(4B)(a) (IDFC First Bank); no intent to evade, so no penalty. (Para 11)
ST-3 and ER-1 returns show the credit stayed untouched at Anna Nagar until its reversal. (Para 12)
- Respondent (Revenue):
Setting-up services ceased to be input services from 01.04.2011; the land had no nexus with Anna Nagar's output services; the factory was registered only in 2016; credit was taken in an unrelated registration after surrendering ISD registration. (Para 13)
D. Court's Observations & Analysis :
- Re: Issue (i): Section 73(4B)
The words 'where it is possible to do so' prevent an absolute bar (ANI Technologies, Bombay HC, SLP dismissed 29.01.2026); proceedings must still end within a reasonable time (Steel Authority of India, Madras HC). (Para 16)
Held: the order is not void merely because it was passed after six months; reasonableness of the delay is left undecided because the appeal succeeds on merits. (Para 16)
- Re: Issue (ii): Lease premium as input service
The 2011 amendment narrowed only the inclusive part; the main limb and the exclusions (which cover construction, not renting) were untouched. (Para 17)
A lease of the factory land is plainly used in relation to manufacture, following Kellogs India, Zuari Cement, Nemak Aluminium Castings and Komatsu India; no contrary decision was cited. (Paras 18–19)
The Supreme Court's dismissal of the SLP in Shell India declares no law (Fuljit Kaur), so the conclusion rests on the text of Rule 2(l). (Para 19)
Vacant land, later commencement of production and late factory registration are no bar; Rule 4(7) ties credit to the invoice. (Para 20)
Held: the tax on the lease premium was paid on an input service of the appellant as a manufacturer. (Para 20)
- Re: Issue (iii): Credit in the wrong registration
The lease was not an input service for the Anna Nagar output services, but entitlement flows from the definition to the legal person, not to each registration (Royal Enfield; Pipavav Shipyard). (Paras 21–22)
Before 01.04.2016 Rule 7 did not compel ISD distribution, and missing ISD registration is curable (Dashion; Pricol; Circular No. 1063/2/2018-CX). (Para 23)
Month-by-month ST-3 returns show the Anna Nagar balance never fell below the lease credit and none was used for excise duty, contrary to the adjudicator's finding. (Para 24)
Held: an admissible credit is not 'taken wrongly' because it was first entered in another registration of the same person; the demand of ₹2,31,65,730 is unsustainable. (Para 25)
- Re: Issue (iv): Interest and penalty
No interest is due on an admissible credit; Rule 14 provides for interest only where credit is taken and utilised wrongly (Strategic Engineering, Madras HC; Bill Forge; Gokaldas Images). (Para 27)
The notice was issued under Section 73(1) alone, within the normal period counted from the revised return (Rule 7B), so post-2015 Section 78 could not apply. Even on the older law, no suppression or intent was shown: the credit was disclosed in the return and a legal opinion evidences bona fides. (Paras 28–29)
The adjudicator wrongly treated a true statement as a misstatement, ignored the Department's own returns and added a penalty ground not in the notice (Toyo Engineering; Champdany Industries). (Para 30)
Held: interest and penalty set aside. (Paras 27–30)
Notable Observations: “A credit admissible to the person who took it is not taken wrongly merely because it was first entered in the account of another registration of the same person.” (Para 25); “A penalty of Rs.2,31,65,730/-, equal to the entire credit, in a case where the Revenue suffered no loss, is not the measured exercise of a quasi judicial power.” (Para 30)
E. Decision & Directions :
1. Appeal allowed; Order-in-Original No. 29/2018 dated 12.03.2018 set aside with consequential relief. (Para 32)
2. The credit of ₹2,31,65,730 reversed at the Anna Nagar registration shall not be taken again there or refunded. (Paras 26, 32)
3. The fresh availment of the credit in the Mahindra World City factory's ER-1 return for March 2017, and its carry-forward, are left open for examination in accordance with law, subject to limitation. (Paras 26, 31–32)
Costs: Not stated in judgment.
Separate Opinions: None (order authored by Ajayan T.V., Member (Judicial), for the Bench).
F. Legal Provisions Discussed & Precedents Cited :
- CENVAT Credit Rules, 2004 – Rule 2(l) – definition of input service; 'setting up' omitted from the inclusive part by Notification No. 3/2011-CE (NT) w.e.f. 01.04.2011.
- CENVAT Credit Rules, 2004 – Rules 3(1), 3(4), 4(7), 7, 14 and 15(3) – entitlement, utilisation, timing, ISD distribution, recovery with interest, penalty.
- Finance Act, 1994 – Sections 73(1), 73(4B)(a), 73(6), 75 and 78; Service Tax Rules, 1994 – Rule 7B (revised return).
- Board Circular No. 1063/2/2018-CX dated 16.02.2018 – acceptance of Dashion on ISD non-registration.
- Doctrines applied: means-and-includes reading of definitions; entitlement attaches to the legal person, not the registration; dismissal of an SLP declares no law.
- ANI Technologies Pvt. Ltd. v. Union of India, 2025 (11) TMI 517 (Bom.), SLP dismissed 2026 (2) TMI 183 (SC) – Followed.
- Meena Fire Works Industries v. Commissioner, (2025) 34 Centax 7 (Tri. Mad.) – Followed.
- Kellogs India Pvt. Ltd. v. Commissioner, 2020 (7) TMI 414 (CESTAT Hyderabad) and Zuari Cement Ltd. v. Commissioner, 2025 (12) TMI 449 (CESTAT Bangalore) – Followed.
- Nemak Aluminium Castings (I) Pvt. Ltd., 2025 (7) TMI 335 and Komatsu India (P) Ltd., 2026 (3) TMI 1628 (CESTAT Chennai) – Followed (binding coordinate Benches).
- Shell India Pvt. Ltd., 2021 (11) TMI 1127 (CESTAT Bangalore), affirmed on a narrower basis by the Karnataka HC – Distinguished as to scope.
- Royal Enfield v. Commissioner, 2026 (10) TMI 1163 (CESTAT Chennai) and CCE v. Pipavav Shipyard Ltd., (2023) 4 Centax 246 (Guj.) – Followed.
- CCE v. Dashion Ltd., 2016 (41) S.T.R. 884 (Guj.) and CCE v. Pricol Ltd., 2021 (48) G.S.T.L. 235 (Mad.) – Followed.
- CCE, Madurai v. Strategic Engineering (P) Ltd., 2014 (310) E.L.T. 509 (Mad.) – Followed.
- Commissioner of Customs v. Toyo Engineering India Ltd., 2006 (201) E.L.T. 513 (S.C.) – Relied on.
- Fuljit Kaur v. State of Punjab, 2010 (262) E.L.T. 40 (S.C.) – Relied on.
G. Case Details :
- Case / Party Name: M/s Heat and Control (South Asia) Private Limited, Mahindra World City, Chengalpattu v. Principal Commissioner of GST & Central Excise, Chennai North Commissionerate
- Case Number(s): Excise Appeal No. 41410 of 2018 (Final Order No. 41164/2026), arising out of Order-in-Original No. 29/2018 CH.N.GST dated 12.03.2018
- Coram / Judges: Vasa Seshagiri Rao, Member (Technical) and Ajayan T.V., Member (Judicial) – Division Bench; authored by Ajayan T.V.
- Counsel Appearances: For the Appellant: Ms. Disha Jain, Advocate. For the Respondent: Mr. M. Selvakumar, Authorised Representative.
Disclaimer: This summary is an editorial aid and does not form part of the judgment. Refer to the original judgment before citing.
Full Judgement / Attachment
Full Judgement
Frequently asked questions about Indirect Taxes and Customs (CBIC)
- What is the CBIC?
- The Central Board of Indirect Taxes and Customs (CBIC), in the Department of Revenue, Ministry of Finance, administers customs, central excise and the Central GST and IGST. It issues notifications, circulars and instructions that field formations follow.
- How do importers and exporters file customs documents?
- Bills of entry and shipping bills are filed electronically through ICEGATE, the CBIC's customs e-commerce gateway. Most bills of entry are assessed under the Faceless Assessment system.
- How do I appeal against a customs order?
- A first appeal lies to the Commissioner (Customs Appeals) within 60 days, with a pre-deposit of 7.5 per cent of the duty in dispute. A further appeal lies to the Customs, Excise and Service Tax Appellate Tribunal (CESTAT) within three months, with a pre-deposit of 10 per cent.
- Where are CBIC notifications published?
- Notifications and circulars on customs, GST and central excise are published on the CBIC website (cbic.gov.in) and in the Gazette of India, under separate series for tariff and non-tariff notifications.
- How can White Collar Professional help with a customs or CBIC matter?
- Post your requirement on White Collar Professional to receive proposals from verified Chartered Accountants, customs brokers and Advocates, compare them, and pay securely through the platform. This page also tracks the latest customs or CBIC CBIC and customs updates as they are reported.