← back
Must-ReadIndirect Taxes and Customs (CBIC)
No Extended Period for Interpretational Disputes: CESTAT Allahabad Quashes ₹7.24 Crore Service Tax Demand on Government Works Contractor
Court / Authority
Indirect Taxes and Customs (CBIC)
Update / Judgement Date
02 Nov 2026
Case No.
70016/2025
Source
CUSTOM, EXCISE AND SERVICE TAX APPELANT TRIBUNAL
Author
Arshee Saifi — WCP Legal Desk
Reading Time
7 min read
View Count
1
GST
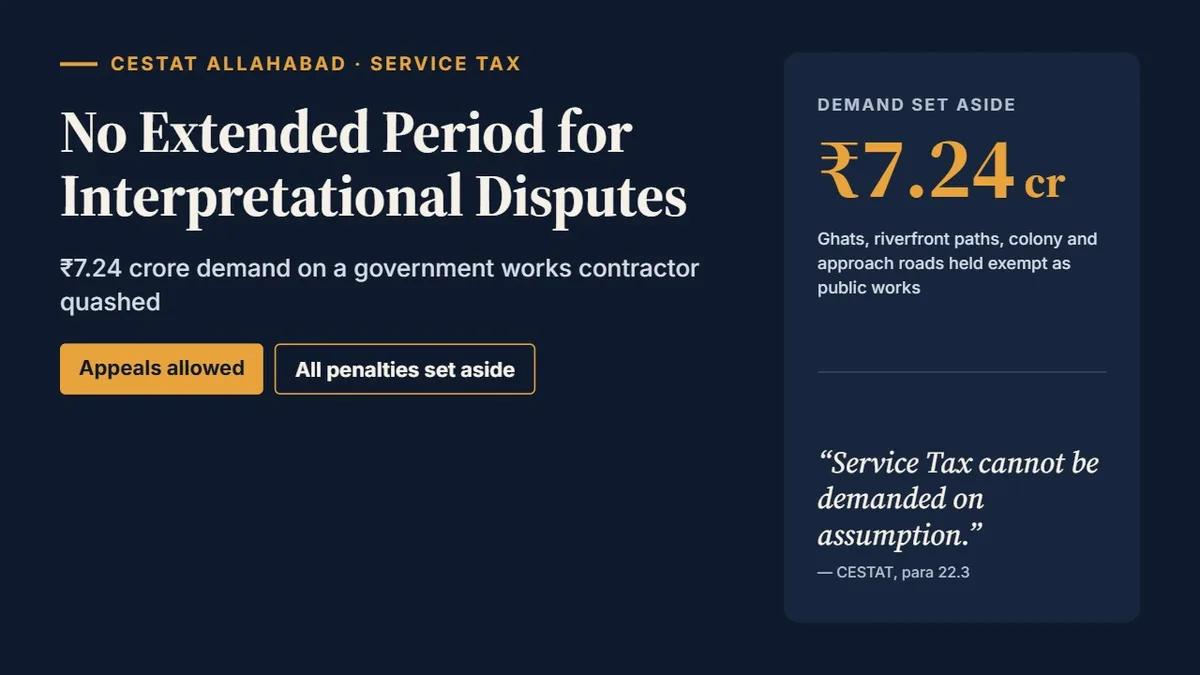
A Lucknow contractor executing works mainly for Government departments was assessed ₹7,24,12,305 in service tax for April 2016 to June 2017 – ₹4.48 crore on forward charge and ₹2.76 crore on reverse charge – with penalties on the company and its director; the show cause notice issued on 08.10.2021 invoked the extended period (Paras 1–6). Taking the 14 heads issue-wise, the Tribunal held that a pakka ghat built to prevent dam erosion and flood-security works were exempt as dam/irrigation works under Entry 12(d), that a riverfront pathway, colony roads, a cobble-stone road, a highway-widening sub-contract and an approach road to State warehouses were public roads under Entry 13(a), and that interior renovation of the Kanpur Development Authority office was repair of a civil structure under Entry 12A(a) (Paras 11–19). Reverse-charge demands on labour charges, sub-contract expenses and royalty deductions failed because they rested on assumption with no identified transaction (Paras 20–23). As every issue was interpretational, ST-3 returns had been filed and the data came from the appellant's own books, the extended period could not be invoked and the entire demand was time-barred (Para 24). Both appeals were allowed and all penalties set aside (Paras 25–26).
Key Proposition: Where a service tax demand turns entirely on the interpretation of exemption entries, the assessee has regularly filed ST-3 returns and the figures are taken from its own books of account, there is no fraud or suppression and the extended period of limitation cannot be invoked.
A. Background / Synopsis :
- The appellant company carries out construction work for clients such as PWD, the Irrigation Department and U.P. Avas Vikas Parishad; the second appellant is its director. (Paras 1, 23.2)
- Enquiry by DGEI → show cause notice dated 08.10.2021 for 01.04.2016 to 30.06.2017 → Order-in-Original No. 47/PC/ST/LKO/2023-24 dated 01.03.2024 by the Principal Commissioner, CGST Lucknow. (Paras 1, 5, 6)
- The order confirmed ₹7,24,12,305 (₹446.7 lakh forward charge on nine projects; ₹276.97 lakh reverse charge on GTA, legal, manpower, works contract and royalty heads), with penalties under Sections 78, 77(1)(c) and 77(2), and ₹1,00,000 on the director under Section 78A. (Paras 1–4)
- Relief sought: setting aside of the demand and penalties on merits and on limitation. (Para 6)
B. Issues For Consideration :
- Whether the forward-charge works qualified for exemption under Entries 12(d), 12A(a), 13(a) or 29(h) of Notification No. 25/2012-ST.
- Whether a sub-contractor must pay service tax where the main contractor has already paid it.
- Whether reverse-charge tax was payable on GTA, legal, labour, sub-contract and royalty payments.
- Whether the extended period of limitation could be invoked, and whether penalties survive.
C. Submissions Of Parties :
- Appellants:
- Each project is covered by one or other entry of Notification No. 25/2012-ST, supported by certificates from the Government departments concerned. (Paras 6, 11–19)
- For the Basti Medical College sub-contract, the main contractor (U.P. Rajkiya Nirman Nigam) had paid ₹61,64,767, so demanding it again is double taxation and revenue-neutral; relied on BCC Developers and Vodafone Essar South. (Para 12.2)
- Labour was hired daily with material supplied by the appellant, royalty was merely deducted by clients, and only small amounts (about ₹10,000 GTA and ₹4,800 legal) were conceded. (Paras 20.2, 21.1, 22.2, 23.2)
- The whole demand fell outside the normal 30-month period; returns were filed and all amounts were in the books. (Paras 6, 24.1)
- Respondent (Revenue):
- Supported the impugned order and argued the appellants had not produced the required documents during investigation. (Para 8)
- Court's Observations & Analysis :
- Re: Issue (i): Exemption under Notification No. 25/2012-ST
- A pakka ghat on the Yamuna at Arail, certified by the Flood Work Division as built to avoid dam erosion, and flood-security work on the Rapti at Gorakhpur (contract extended to 30.06.2017) relate to dams and irrigation works under Entry 12(d). (Paras 11.2, 13.2)
- A concrete pathway and parking on the Gomti riverfront used by the public, cobble-stone road work in Lucknow, roads in Sapna Enclave (part of Vrindavan Yojana), widening of the Lucknow–Varanasi road and approach roads to U.P. State Warehousing godowns are roads for general public use under Entry 13(a). (Paras 14.4, 16.4, 17.4, 18.4, 19.1)
- Interior decoration of the Kanpur Development Authority office is repair of a civil structure for a governmental authority under Entry 12A(a). (Para 15.4)
- Held: all nine forward-charge projects other than the Basti Medical College were exempt on merits. (Paras 11–19)
- Re: Issue (ii): Sub-contractor's liability
- Entry 12(a) was withdrawn from 01.03.2015, so no exemption was available. Despite earlier decisions holding otherwise, the Larger Bench in Melange Developers settled that the sub-contractor is liable.
- Held: liable on merits, but given the conflicting decisions the extended period could not be invoked, so the demand is set aside on limitation. (Para 12.2)
- Re: Issue (iii): Reverse-charge demands
- Only actual GTA freight and payments to an advocate attract reverse charge; loading charges, supplier freight and payments to CAs, company secretaries and architects do not. (Paras 20.3, 21.2)
- The Department identified no contract for manpower supply or works contract; labour charges and sub-contract expenses cannot be taxed on assumption. (Paras 22.3–22.4)
- No transaction of right to use natural resources was identified, and U.P. Avas Vikas Parishad is neither Government nor a local authority. (Para 23.3)
- Held: demands under these heads set aside. (Paras 20–23)
- Re: Issue (iv): Limitation and penalties
- Following Shervani Industries, International Merchandising Co. (SC), Rungta Sons, G D Goenka and Munna Constructions, the extended period is not available where the issues are interpretational, returns were filed and the information came from the books. (Paras 24.2–24.5)
- Held: entire demand time-barred; penalties on the company and on the director set aside. (Paras 24.6, 25)
- Notable Observations: “Service Tax cannot be demanded on assumption.” (Para 22.3); “We find that the construction of concrete pathway is nothing but a public road.” (Para 14.4)
D. Decision & Directions :
- Impugned Order-in-Original dated 01.03.2024 set aside; both appeals allowed with consequential relief as per law. (Para 26)
- Penalties under Sections 77 and 78 on the company and under Section 78A on the director set aside. (Para 25)
- Costs: Not stated in judgment.
- Separate Opinions: None.
- Legal Provisions Discussed & Precedents Cited :
- Finance Act, 1994 – Sections 77(1)(c), 77(2), 78 and 78A – penalties imposed and set aside.
- Finance Act, 1994 – Section 66D (negative list) – Government services taxable from 01.04.2016, the basis of the royalty demand.
- Notification No. 25/2012-ST dated 20.06.2012 – Entries 12(d), 12A(a), 13(a) and 29(h) – mega exemption for works for Government, public roads and sub-contractors.
- Notification No. 30/2012-ST dated 20.06.2012 – reverse charge on manpower supply, legal services, works contract and Government services.
- Doctrine applied: extended period of limitation not available where the dispute is interpretational and there is no suppression.
- Melange Developers Pvt. Ltd., 2020 (33) GSTL 116 (Larger Bench) – Followed.
- BCC Developers & Promoters Pvt. Ltd., 2017 (52) STR 22 – Referred to.
- Vodafone Essar South Ltd., 2020 (43) GSTL 249 – Relied on.
- Shervani Industries Syndicate Ltd., 2009 (14) S.T.R. 486 (Tri.-Delhi) – Relied on.
- International Merchandising Company, 2022 (67) GSTL 129 (SC) – Relied on.
- Rungta Sons Pvt. Ltd., 2024 (22) Centax 495 – Relied on.
- G D Goenka Pvt. Ltd., Final Order No. 51088/2023 dated 21.08.2023 – Relied on.
- Munna Constructions, 2025 (26) Centax 476 – Relied on.
E. Case Details :
- Case / Party Name: M/s G. S. Express Pvt. Ltd. (Appellant No. 1) and Shri Sandeep Anand, Director (Appellant No. 2) v. Principal Commissioner, CGST & Central Excise, Lucknow
- Case Number(s): Service Tax Appeal No. 70017 of 2025 and Service Tax Appeal No. 70016 of 2025 (Final Order Nos. 70562–70563/2026)
- Coram / Judges: P. K. Choudhary, Member (Judicial) and K. Anpazhakan, Member (Technical) – Division Bench; authored by P. K. Choudhary
- Counsel Appearances: For the Appellants: Shri Kapil Vaish, Advocate. For the Respondent: Shri Jaishankar Prakash Upadhyay, Authorised Representative.
Disclaimer: This summary is an editorial aid and does not form part of the judgment. Refer to the original judgment before citing.
Full Judgement / Attachment
Full Judgement
Frequently asked questions about Indirect Taxes and Customs (CBIC)
- What is the CBIC?
- The Central Board of Indirect Taxes and Customs (CBIC), in the Department of Revenue, Ministry of Finance, administers customs, central excise and the Central GST and IGST. It issues notifications, circulars and instructions that field formations follow.
- How do importers and exporters file customs documents?
- Bills of entry and shipping bills are filed electronically through ICEGATE, the CBIC's customs e-commerce gateway. Most bills of entry are assessed under the Faceless Assessment system.
- How do I appeal against a customs order?
- A first appeal lies to the Commissioner (Customs Appeals) within 60 days, with a pre-deposit of 7.5 per cent of the duty in dispute. A further appeal lies to the Customs, Excise and Service Tax Appellate Tribunal (CESTAT) within three months, with a pre-deposit of 10 per cent.
- Where are CBIC notifications published?
- Notifications and circulars on customs, GST and central excise are published on the CBIC website (cbic.gov.in) and in the Gazette of India, under separate series for tariff and non-tariff notifications.
- How can White Collar Professional help with a customs or CBIC matter?
- Post your requirement on White Collar Professional to receive proposals from verified Chartered Accountants, customs brokers and Advocates, compare them, and pay securely through the platform. This page also tracks the latest customs or CBIC CBIC and customs updates as they are reported.