ITAT Mumbai Deletes Ad-Hoc Disallowance on Labour Expenses; Holds Suspicion Cannot Replace Proof
Court / Authority
Income Tax Tribunal
Update / Judgement Date
29 Aug 2026
Source
WCP News Bulletin
Author
Manas Yadav — WCP Legal Desk
Reading Time
2 min read
View Count
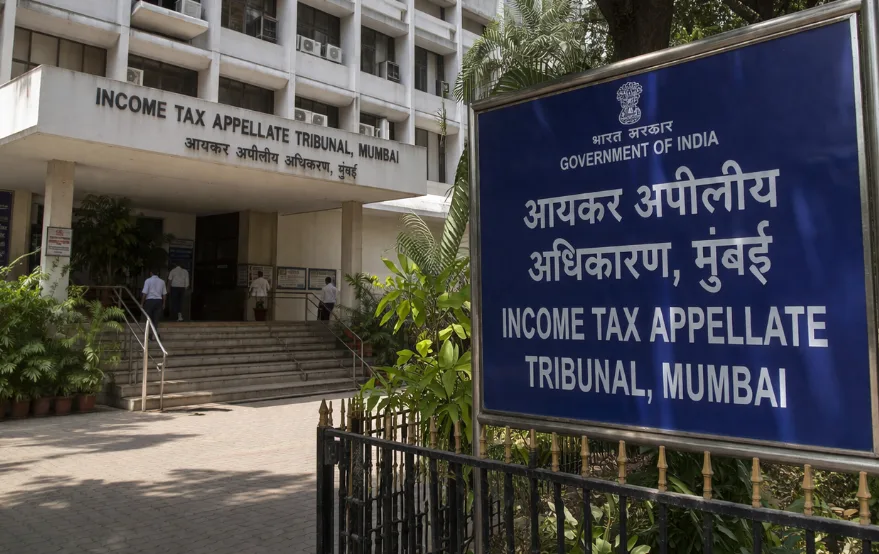
The Income Tax Appellate Tribunal (ITAT), Mumbai Bench “E”, has deleted an ad-hoc disallowance of ₹16.71 lakh sustained by the Commissioner (Appeals), holding that labour expenditure cannot be disallowed merely on suspicion in the absence of cogent evidence.
The assessee, engaged in the business of manufacturing and trading gold jewellery, had claimed labour expenses of ₹4.92 crore. The Assessing Officer (AO), based on bank analysis and verification reports, treated payments made to five labour contractors as non-genuine, primarily noting immediate cash withdrawals after cheque deposits and absence of contractors at recorded addresses. Consequently, the AO disallowed ₹1.67 crore as bogus expenditure.
On appeal, the Commissioner (Appeals) accepted the business model and evidentiary documentation but sustained a 10% disallowance (₹16.71 lakh) on a protective basis.
Before the Tribunal, the assessee demonstrated that all payments were made through banking channels, supported by invoices, confirmations, and statutory compliance. The Tribunal noted that the books of account were not rejected under Section 145(3), and no discrepancy in stock or turnover was identified. It further observed that all contractors responded to notices under Section 133(6), and no material evidence established any round-tripping of funds.
Crucially, the Tribunal held that in the jewellery industry, immediate cash withdrawals by labour contractors are commercially plausible, given the nature of payments to small artisans. It also found deficiencies in the verification exercise, including incorrect address identification.
Rejecting the “split-the-difference” approach adopted by the Commissioner (Appeals), the Tribunal held that once the expenditure is accepted as genuine, partial disallowance without evidence is arbitrary and unsustainable in law.
Accordingly, the Tribunal deleted the entire addition and allowed the appeal.
Full Judgement / Attachment
Full Judgement
Frequently asked questions about Income Tax Tribunal
- What is the Income Tax Appellate Tribunal (ITAT)?
- The ITAT, set up in 1941, is the second appellate authority in direct tax matters and the final fact-finding body. It hears appeals against orders of the Commissioner (Appeals) and certain other authorities, through benches across India.
- What is the time limit to file an appeal before the ITAT?
- An appeal must be filed within two months from the end of the month in which the order is communicated. This rule has applied since 1 October 2024 and continues under the Income-tax Act, 2025. The Tribunal can condone delay for sufficient cause.
- Can the ITAT stay a tax demand?
- Yes. The Tribunal can stay recovery of a disputed demand while an appeal is pending, usually on deposit of a part of the demand or furnishing security. Stays are granted for a limited period, and the appeal is expected to be decided within it.
- Where does an appeal go after the ITAT?
- An appeal against an ITAT order lies to the High Court, but only on a substantial question of law. A further appeal lies to the Supreme Court.
- How can White Collar Professional help with a ITAT matter?
- Post your requirement on White Collar Professional to receive proposals from verified Chartered Accountants and tax Advocates, compare them, and pay securely through the platform. This page also tracks the latest ITAT ITAT orders as they are reported.