NCLT Allahabad Approves Resolution Plan in Nainital Bank Ltd. v. Rudra AutoTech Engineering Pvt. Ltd.
Court / Authority
Income Tax Tribunal
Update / Judgement Date
30 Aug 2026
Source
WCP News Bulletin
Author
Manas Yadav — WCP Legal Desk
Reading Time
4 min read
View Count
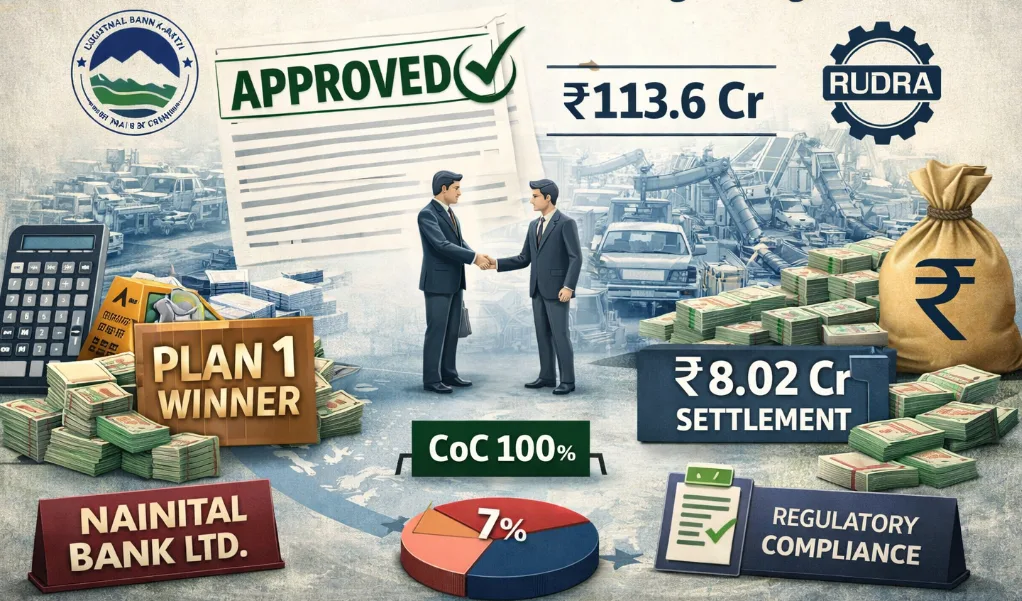
The National Company Law Tribunal, Allahabad Bench (Prayagraj), in its order dated 20 January 2026, approved a resolution plan in the CIRP of Rudra AutoTech Engineering Private Limited, once again affirming the structural dominance of creditor-driven outcomes under the Insolvency and Bankruptcy Code, 2016.
CIRP Background and Competitive Resolution Process
The Corporate Insolvency Resolution Process was initiated on 3 June 2024 upon admission of an application under Section 7 filed by The Nainital Bank Limited, which emerged as the sole financial creditor holding 100 percent voting share in the Committee of Creditors. Following public announcement and claim collation, the financial debt stood at approximately ₹113.6 crore, with negligible operational debt. Unlike cases involving single-plan outcomes, the present CIRP witnessed a relatively competitive process. Multiple rounds of Expression of Interest were conducted, including reissuance of Form G to attract wider participation. Ultimately, three resolution plans were received, and the CoC adopted a Swiss Challenge mechanism to enhance value discovery. One applicant withdrew during this stage, leaving two competing plans which were evaluated under the approved evaluation matrix.
Following negotiations and revisions, the plan submitted by Mr. Raman Sibal was ranked H1 and approved by the sole CoC member with 100 percent voting share. The Resolution Professional issued a Letter of Intent, and the successful resolution applicant furnished performance security of ₹50 lakh in compliance with regulatory requirements. The financial structure of the plan reflects a settlement value of approximately ₹8.02 crore against admitted financial debt exceeding ₹113 crore, indicating a substantial haircut. The plan proposes full payment within 60 days from the effective date, funded through a mix of personal savings, business accruals, unsecured loans, and potential borrowing against assets. Operational creditors receive a nominal payout, while CIRP costs are prioritized in accordance with statutory requirements.
Tribunal Reasoning and Legal Implications
The Tribunal, upon examining the compliance certificate and the terms of the plan, held that the resolution plan satisfies the requirements under Sections 30(2) and 31 of the Code, as well as Regulations 37, 38 and 39 of the CIRP Regulations. The Adjudicating Authority reiterated that once the CoC, even if consisting of a single creditor, approves a plan based on its commercial assessment of feasibility and viability, judicial review remains confined to statutory compliance. The plan envisages complete restructuring of the corporate debtor’s capital, including cancellation of existing equity and fresh infusion of capital by the resolution applicant and his family members. Management and implementation are to be supervised by a monitoring committee comprising the Resolution Professional, nominee of the financial creditor, and nominee of the resolution applicant, ensuring oversight until completion of the plan.
A notable distinction in this case lies in the treatment of avoidance transactions. Unlike several recent rulings where such recoveries accrue to the resolution applicant, the present plan allocates any proceeds from preferential or fraudulent transaction litigation to the secured financial creditor, with litigation costs also borne by it. This reflects the flexibility available to the CoC in structuring economic entitlements arising from contingent recoveries. The Tribunal also clarified that pending avoidance applications under Section 66 would continue and be pursued in terms of the resolution plan. It further emphasized that reliefs and concessions sought by the resolution applicant would be governed strictly by applicable law and relevant judicial precedents, particularly the framework laid down in Ghanshyam Mishra and Sons v. Edelweiss ARC. The approval order renders the resolution plan binding on all stakeholders and brings the moratorium under Section 14 to an end. It also reiterates the statutory protection under Section 32A, insulating the resolution applicant from liabilities arising prior to the commencement of CIRP.
This ruling illustrates the adaptability of the IBC framework, accommodating both competitive bidding mechanisms such as the Swiss Challenge and single-creditor dominated decision-making structures. Even in the face of deep financial haircuts, the Tribunal has maintained doctrinal consistency by prioritizing feasibility, time-bound resolution, and creditor autonomy over distributive considerations, thereby reinforcing the economic logic underpinning India’s insolvency regime.
Full Judgement / Attachment
Full Judgement
Frequently asked questions about Income Tax Tribunal
- What is the Income Tax Appellate Tribunal (ITAT)?
- The ITAT, set up in 1941, is the second appellate authority in direct tax matters and the final fact-finding body. It hears appeals against orders of the Commissioner (Appeals) and certain other authorities, through benches across India.
- What is the time limit to file an appeal before the ITAT?
- An appeal must be filed within two months from the end of the month in which the order is communicated. This rule has applied since 1 October 2024 and continues under the Income-tax Act, 2025. The Tribunal can condone delay for sufficient cause.
- Can the ITAT stay a tax demand?
- Yes. The Tribunal can stay recovery of a disputed demand while an appeal is pending, usually on deposit of a part of the demand or furnishing security. Stays are granted for a limited period, and the appeal is expected to be decided within it.
- Where does an appeal go after the ITAT?
- An appeal against an ITAT order lies to the High Court, but only on a substantial question of law. A further appeal lies to the Supreme Court.
- How can White Collar Professional help with a ITAT matter?
- Post your requirement on White Collar Professional to receive proposals from verified Chartered Accountants and tax Advocates, compare them, and pay securely through the platform. This page also tracks the latest ITAT ITAT orders as they are reported.