ITAT Mumbai: Stamp Duty Value on Date of Agreement to Apply Under Section 50C; Section 54 Deduction Allowed Despite Delayed Registration
Court / Authority
Income Tax Tribunal
Update / Judgement Date
18 Aug 2026
Source
WCP News Bulletin
Author
Manas Yadav — WCP Legal Desk
Reading Time
3 min read
View Count
6
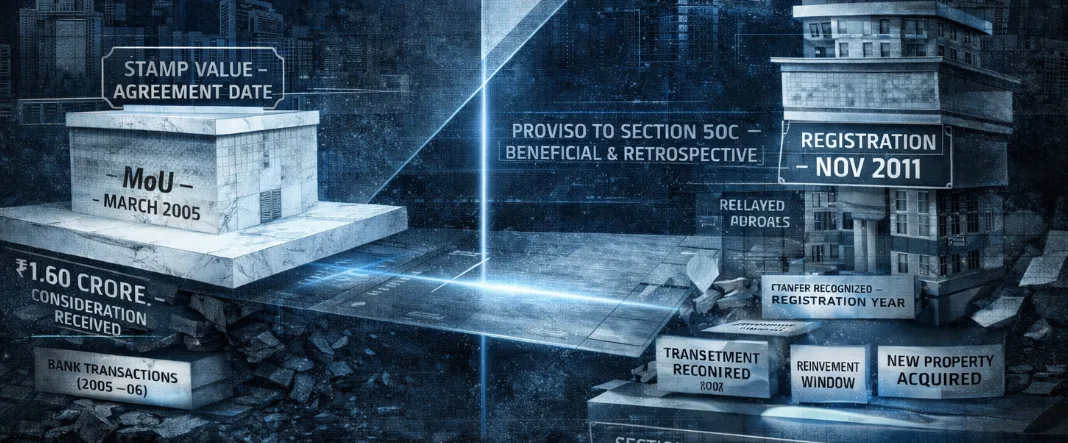
Key Facts and Tribunal Findings
The Mumbai ITAT adjudicated issues relating to capital gains computation under Section 50C and eligibility for deduction under Section 54 in the case of an individual assessee involving sale of immovable property. The assessee had entered into a Memorandum of Understanding (MoU) in March 2005 for sale of a residential flat for ₹1.60 crore and received the entire consideration between 2005–2006 through banking channels. However, due to procedural approvals, including society NOC and government permissions, the final transfer deed was registered only in November 2011. The stamp duty authority valued the property at ₹2.37 crore on the date of registration. The Assessing Officer invoked Section 50C and adopted the stamp duty value as on the date of registration, thereby enhancing the sale consideration. Further, the AO denied deduction under Section 54 on the ground that the assessee had not invested the sale proceeds within the prescribed time from the earlier receipt of consideration and treated the gains as short-term capital gains.
The Tribunal disagreed with the Revenue’s approach. It held that where the date of agreement and date of registration differ, the first proviso to Section 50C(1) permits adoption of stamp duty value as on the date of agreement. The ITAT further held that this proviso, though introduced later, is a beneficial provision and applies retrospectively. Accordingly, the stamp duty valuation as on the date of the MoU must be considered for computing capital gains. On the nature of capital gains, the Tribunal noted that the assessee had held the property since 2004 and therefore the gains were long-term in nature. Regarding deduction under Section 54, the ITAT held that since the capital gain was offered in the year of registration of the transfer deed, the time limit for reinvestment must be computed from that date. As the assessee had purchased a new property within the prescribed period from the date of registration, the deduction was held to be allowable.
Legal Analysis and Practical Implications
The ruling provides significant clarity on the application of Section 50C in cases involving delayed registration of property transactions. By recognizing the retrospective applicability of the first proviso, the Tribunal ensures that taxpayers are not penalized for procedural delays beyond their control when consideration is fixed and substantially received earlier. The decision reinforces the principle that substance of the transaction—particularly the timing of agreement and receipt of consideration—should prevail over the formal date of registration for valuation purposes under Section 50C. On Section 54, the Tribunal adopts a pragmatic interpretation by linking the reinvestment timeline to the year in which capital gains are offered to tax. This approach aligns compliance with practical realities, especially in cases where legal transfer formalities are delayed.
The ruling highlights the importance of maintaining clear documentation of agreements, receipt of consideration, and possession transfer. It also underscores that beneficial provisions aimed at mitigating hardship can be applied retrospectively where justified by judicial interpretation.
Full Judgement / Attachment
Full Judgement
Frequently asked questions about Income Tax Tribunal
- What is the Income Tax Appellate Tribunal (ITAT)?
- The ITAT, set up in 1941, is the second appellate authority in direct tax matters and the final fact-finding body. It hears appeals against orders of the Commissioner (Appeals) and certain other authorities, through benches across India.
- What is the time limit to file an appeal before the ITAT?
- An appeal must be filed within two months from the end of the month in which the order is communicated. This rule has applied since 1 October 2024 and continues under the Income-tax Act, 2025. The Tribunal can condone delay for sufficient cause.
- Can the ITAT stay a tax demand?
- Yes. The Tribunal can stay recovery of a disputed demand while an appeal is pending, usually on deposit of a part of the demand or furnishing security. Stays are granted for a limited period, and the appeal is expected to be decided within it.
- Where does an appeal go after the ITAT?
- An appeal against an ITAT order lies to the High Court, but only on a substantial question of law. A further appeal lies to the Supreme Court.
- How can White Collar Professional help with a ITAT matter?
- Post your requirement on White Collar Professional to receive proposals from verified Chartered Accountants and tax Advocates, compare them, and pay securely through the platform. This page also tracks the latest ITAT ITAT orders as they are reported.









