ITAT Delhi: Transfer Pricing Adjustments on Royalty Deleted; Multiple Corporate Tax Disallowances Decided in Favour of Vodafone Idea
Court / Authority
Income Tax Tribunal
Update / Judgement Date
18 Aug 2026
Source
WCP News Bulletin
Author
Manas Yadav — WCP Legal Desk
Reading Time
3 min read
View Count
3
Key Facts and Tribunal Findings
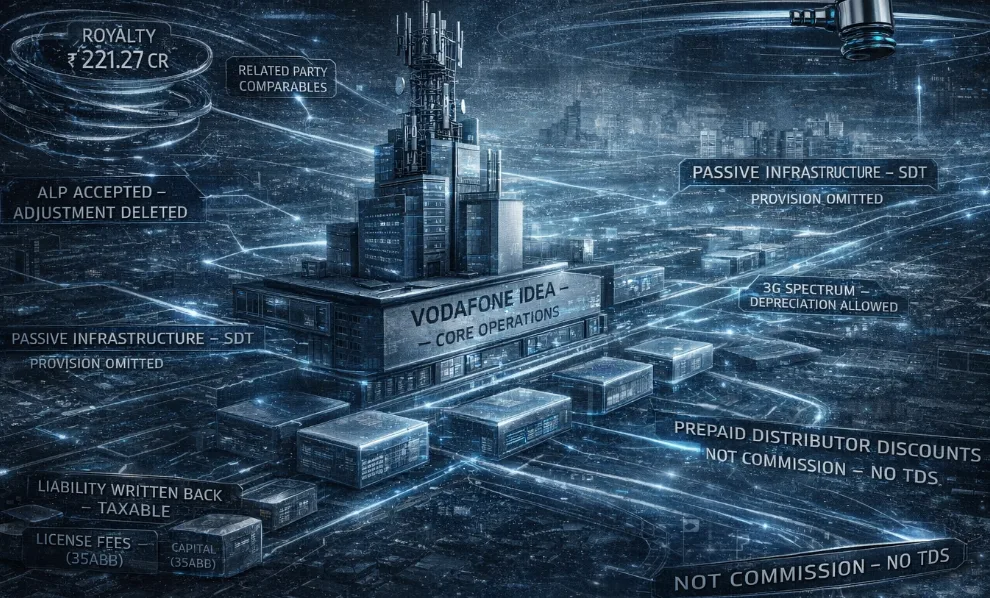
The Delhi ITAT adjudicated a wide-ranging appeal filed by Vodafone Idea Limited for AY 2013–14, involving transfer pricing adjustments and multiple corporate tax disallowances. A primary issue concerned a transfer pricing adjustment of ₹221.27 crore on payment of royalty to an associated enterprise for use of the Vodafone brand. The Tribunal, following its own orders in earlier assessment years, held that the Transfer Pricing Officer’s approach—particularly reliance on related party comparables and rejection of the assessee’s benchmarking—was unsustainable. Accordingly, the adjustment was deleted.
Similarly, the Tribunal deleted the transfer pricing adjustment relating to specified domestic transactions for passive infrastructure charges. It relied on judicial precedent holding that provisions governing such transactions had been omitted from the statute and therefore could not sustain adjustments. The Tribunal also noted the revenue-neutral nature of such transactions. On depreciation relating to 3G spectrum, the ITAT allowed the assessee’s claim under Section 32, following earlier decisions in group cases. Disallowances relating to penalties imposed by the Department of Telecommunications (DoT) for non-compliance with subscriber verification norms and Universal Service Obligation obligations were also deleted, with the Tribunal treating them as contractual rather than penal in nature.
The Tribunal further allowed deduction of asset restoration costs under Section 37, subject to verification, and permitted lease payments to IBM for hardware and services as revenue expenditure. However, addition relating to liabilities written back was upheld, with the Tribunal holding such amounts taxable as business income. On disallowance under Section 40(a)(ia) concerning discounts to prepaid distributors, the ITAT ruled in favour of the assessee, holding that such discounts do not constitute commission and therefore do not attract TDS obligations. Conversely, on license fees, the Tribunal followed Supreme Court precedent and held such payments to be capital in nature, allowing amortization under Section 35ABB.
Legal Analysis and Practical Implications
The ruling consolidates a consistent judicial approach in Vodafone group cases, particularly on transfer pricing disputes. The Tribunal’s rejection of adjustments based on related party comparables reinforces the requirement that benchmarking must rely on uncontrolled transactions, preserving methodological integrity under transfer pricing regulations. The deletion of adjustments relating to specified domestic transactions reflects the legal consequence of statutory omission, underscoring that pending proceedings cannot survive where the enabling provision has been removed without a saving clause.
On corporate tax issues, the decision distinguishes between contractual and statutory penalties, allowing deductions where payments arise from business obligations rather than legal infractions. The ruling also reiterates that accounting treatment does not determine tax deductibility, particularly in the context of lease arrangements and asset restoration costs. The judgment provides clarity on recurring telecom sector issues, including spectrum payments, infrastructure sharing, and distributor arrangements. It offers significant relief to taxpayers by aligning tax treatment with commercial substance while adhering to established judicial precedents.
Full Judgement / Attachment
Full Judgement
Frequently asked questions about Income Tax Tribunal
- What is the Income Tax Appellate Tribunal (ITAT)?
- The ITAT, set up in 1941, is the second appellate authority in direct tax matters and the final fact-finding body. It hears appeals against orders of the Commissioner (Appeals) and certain other authorities, through benches across India.
- What is the time limit to file an appeal before the ITAT?
- An appeal must be filed within two months from the end of the month in which the order is communicated. This rule has applied since 1 October 2024 and continues under the Income-tax Act, 2025. The Tribunal can condone delay for sufficient cause.
- Can the ITAT stay a tax demand?
- Yes. The Tribunal can stay recovery of a disputed demand while an appeal is pending, usually on deposit of a part of the demand or furnishing security. Stays are granted for a limited period, and the appeal is expected to be decided within it.
- Where does an appeal go after the ITAT?
- An appeal against an ITAT order lies to the High Court, but only on a substantial question of law. A further appeal lies to the Supreme Court.
- How can White Collar Professional help with a ITAT matter?
- Post your requirement on White Collar Professional to receive proposals from verified Chartered Accountants and tax Advocates, compare them, and pay securely through the platform. This page also tracks the latest ITAT ITAT orders as they are reported.









