ITAT Delhi Upholds Deletion of ₹2.89 Crore Additions; Dismisses Revenue Appeal in Lord Shiva Construction Case
Court / Authority
Income Tax Tribunal
Update / Judgement Date
26 Aug 2026
Source
WCP News Bulletin
Author
Manas Yadav — WCP Legal Desk
Reading Time
2 min read
View Count
Key Facts and Tribunal Findings
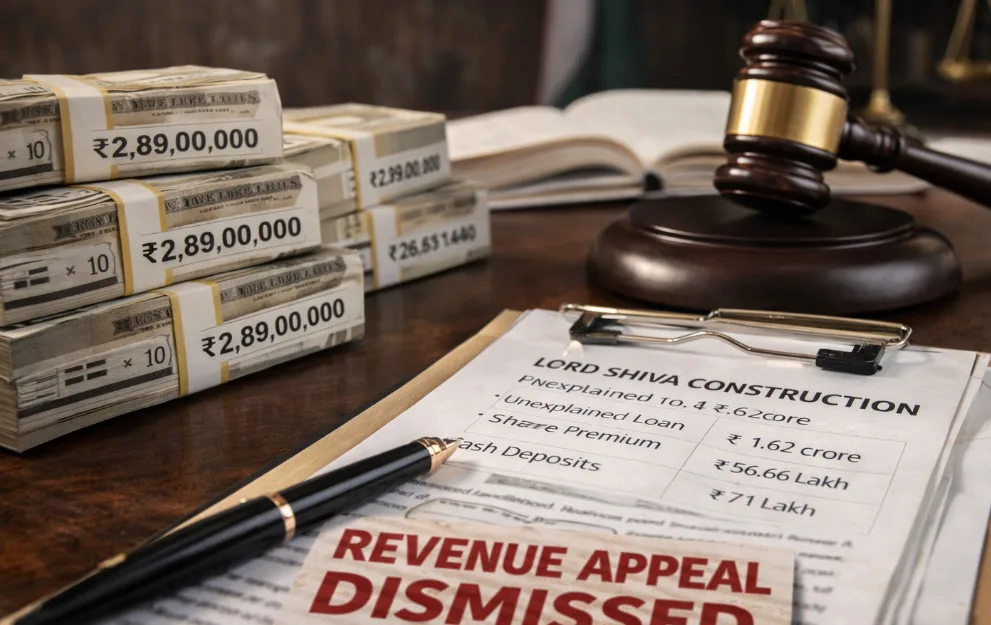
The Income Tax Appellate Tribunal (ITAT), Delhi Bench, dismissed the Revenue’s appeal against Lord Shiva Construction Co. Pvt. Ltd. for Assessment Year 2018–19, upholding deletion of multiple additions made under Sections 68 and 56(2)(viib) of the Income Tax Act.
The Assessing Officer had made three principal additions: ₹1.62 crore as unexplained loan under Section 68 from sister concern M/s Vidhata Contractors & Builders Pvt. Ltd., ₹56.66 lakh as unexplained share premium under Section 56(2)(viib), and ₹71 lakh as unexplained cash deposits under Section 68. The CIT(A) deleted all additions after examining documentary evidence furnished by the assessee.
On the issue of unsecured loan, the Tribunal noted that the assessee had established the identity, creditworthiness, and genuineness of the lender through PAN, audited financial statements, bank statements, and confirmation responses under Section 133(6). The Revenue failed to rebut these findings.
Regarding share premium, the Tribunal upheld the CIT(A)’s finding that the valuation report obtained from a Chartered Accountant was valid, as the assessee had adopted the book value method. It held that the requirement of a merchant banker’s report under amended Rule 11UA applies only where the Discounted Cash Flow method is used and was not applicable in the present case.
On cash deposits, the Tribunal observed that the assessee demonstrated a clear nexus between earlier cash withdrawals and subsequent deposits through cash books and bank records. The explanation was consistent with the nature of construction business operations, and no contrary evidence was brought by the Revenue.
Finding no infirmity in the CIT(A)’s order, the Tribunal dismissed the Revenue’s appeal in entirety.
Full Judgement / Attachment
Full Judgement
Frequently asked questions about Income Tax Tribunal
- What is the Income Tax Appellate Tribunal (ITAT)?
- The ITAT, set up in 1941, is the second appellate authority in direct tax matters and the final fact-finding body. It hears appeals against orders of the Commissioner (Appeals) and certain other authorities, through benches across India.
- What is the time limit to file an appeal before the ITAT?
- An appeal must be filed within two months from the end of the month in which the order is communicated. This rule has applied since 1 October 2024 and continues under the Income-tax Act, 2025. The Tribunal can condone delay for sufficient cause.
- Can the ITAT stay a tax demand?
- Yes. The Tribunal can stay recovery of a disputed demand while an appeal is pending, usually on deposit of a part of the demand or furnishing security. Stays are granted for a limited period, and the appeal is expected to be decided within it.
- Where does an appeal go after the ITAT?
- An appeal against an ITAT order lies to the High Court, but only on a substantial question of law. A further appeal lies to the Supreme Court.
- How can White Collar Professional help with a ITAT matter?
- Post your requirement on White Collar Professional to receive proposals from verified Chartered Accountants and tax Advocates, compare them, and pay securely through the platform. This page also tracks the latest ITAT ITAT orders as they are reported.