ITAT Kolkata Reduces Profit Estimation to 4% and Deletes Penalties Under Sections 271B and 271(1)(b) in Wholesale Medicine Case
Court / Authority
Income Tax Tribunal
Update / Judgement Date
22 Aug 2026
Source
WCP News Bulletin
Author
Manas Yadav — WCP Legal Desk
Reading Time
2 min read
Key Facts and Tribunal Findings
The Income Tax Appellate Tribunal (ITAT), Kolkata Bench, partly allowed the quantum appeal and fully allowed penalty appeals filed by Md. Babar Ali for Assessment Year 2020–21, modifying profit estimation and deleting penalties imposed under Sections 271B and 271(1)(b) of the Income Tax Act. The assessee, engaged in wholesale trading of medicines, had not initially filed a return of income. Based on GST data reflecting transactions of ₹4.47 crore, the Assessing Officer reopened the case under Section 147. In response, the assessee filed a return declaring turnover of ₹2.35 crore and income at 2.05%.
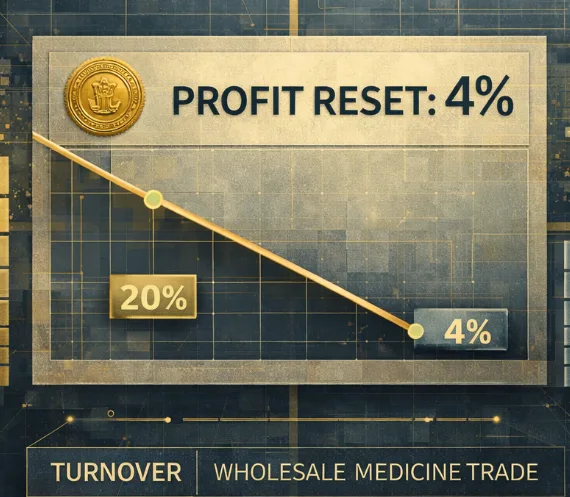
Due to non-production of books of account and supporting documents, the Assessing Officer completed assessment under Section 147 read with Section 144B by estimating income at 20% of turnover, resulting in assessed income of ₹47.17 lakh. The CIT(A) partly granted relief by accepting the assessee’s turnover but estimating net profit at 5%, restricting the addition. On further appeal, the Tribunal observed that neither the Assessing Officer nor the CIT(A) had relied on comparable cases for determining profit rates. Considering the nature of the wholesale medicine trade, where margins are typically thin, the Tribunal held that a net profit rate of 4% would be reasonable. The income was accordingly recomputed.
In separate penalty appeals, the Tribunal deleted penalty under Section 271B for delayed filing of audit report, accepting the assessee’s explanation of reasonable cause, including lack of technical knowledge and reliance on a tax consultant. It also deleted penalty under Section 271(1)(b), noting inconsistent application by the CIT(A) and absence of clear justification for partial penalty sustenance.
Legal Analysis
The Tribunal reiterated that estimation of income must be based on reasonable and rational parameters, ideally supported by comparable industry benchmarks. Arbitrary application of profit rates without supporting material was held to be unsustainable. On penalties, the decision emphasizes the role of “reasonable cause” under Section 273B, particularly in cases involving procedural lapses arising from genuine hardship. The Tribunal also highlighted that inconsistent or selective imposition of penalties, without clear reasoning, cannot be sustained.
The ruling reflects a calibrated approach, balancing revenue protection with fairness in estimation and penalty proceedings.
Full Judgement / Attachment
Full Judgement









