ITAT Mumbai: Addition on Unsecured Loan Deleted Where Creditor Previously Accepted; Remand on Advances and Interest Income in Chandwani Case
Court / Authority
Income Tax Tribunal
Update / Judgement Date
18 Aug 2026
Source
WCP News Bulletin
Author
Manas Yadav — WCP Legal Desk
Reading Time
3 min read
View Count
3
Key Facts and Tribunal Findings
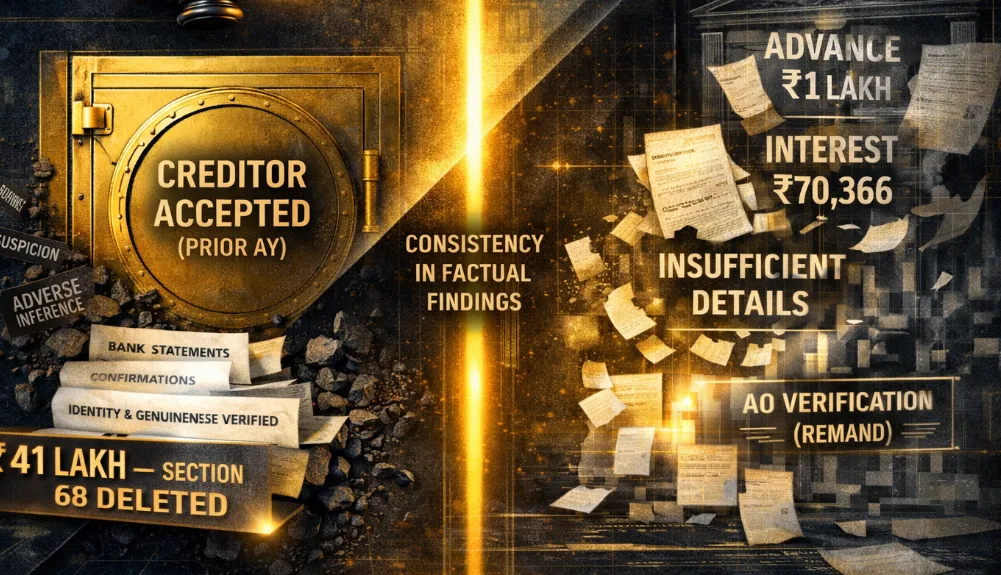
The Mumbai ITAT adjudicated the appeal of an individual assessee, Mahesh Vishindas Chandwani, concerning additions relating to unsecured loans, advances, and interest income for the relevant assessment year. The principal issue involved an addition of ₹41 lakh under Section 68 on account of an unsecured loan received from one Mr. Dipak Bhatija. The Assessing Officer and the CIT(A) had doubted the creditor’s creditworthiness and genuineness, relying in part on earlier adverse findings.
The Tribunal, however, noted that in prior proceedings for AY 2009–10, the same creditor had been subject to scrutiny. Pursuant to directions of the ITAT in that earlier year, the Assessing Officer had re-examined the creditor and ultimately accepted the genuineness of the loan in a set-aside assessment. The Tribunal found that the present loan pertained to the same creditor, and the transaction was supported by documentary evidence, including bank statements and confirmations. In light of the Department’s own acceptance of the creditor’s identity and genuineness in earlier proceedings, the ITAT held that there was no justification to sustain the addition on identical facts. Accordingly, the addition of ₹41 lakh was deleted.
On the issue of ₹1 lakh advanced to another individual, the Tribunal observed that the assessee had failed to conclusively establish the identity and details of the recipient during assessment. However, considering that certain documents were subsequently placed on record, the ITAT remanded the matter to the Assessing Officer for fresh verification. Similarly, with respect to addition of ₹70,366 towards interest income allegedly not offered to tax, the Tribunal noted that the assessee claimed to have declared the income in a subsequent assessment year. As this aspect had not been properly verified, the issue was restored to the Assessing Officer to ensure that the same income is not taxed twice.
Legal Analysis and Practical Implications
The ruling underscores a key evidentiary principle in tax proceedings: where the identity and genuineness of a creditor have already been accepted by the Department in earlier proceedings after due verification, it is impermissible to disregard the same without fresh material or distinguishing facts. The Tribunal effectively applied consistency in factual findings to prevent repetitive additions under Section 68. This decision highlights the importance of maintaining continuity in assessments, particularly in cases involving recurring transactions with the same parties. Once a creditor’s credentials are established and accepted, the burden on the Revenue to dislodge that position in subsequent years becomes significantly higher. At the same time, the Tribunal’s approach to the other issues reflects a balanced procedural stance. In cases where documentation is incomplete or verification is lacking, remand remains the appropriate course to ensure factual accuracy rather than outright deletion. The decision also reiterates that income cannot be subjected to double taxation across assessment years, reinforcing the need for proper verification of timing and disclosure of income streams.
Full Judgement / Attachment
Full Judgement
Frequently asked questions about Income Tax Tribunal
- What is the Income Tax Appellate Tribunal (ITAT)?
- The ITAT, set up in 1941, is the second appellate authority in direct tax matters and the final fact-finding body. It hears appeals against orders of the Commissioner (Appeals) and certain other authorities, through benches across India.
- What is the time limit to file an appeal before the ITAT?
- An appeal must be filed within two months from the end of the month in which the order is communicated. This rule has applied since 1 October 2024 and continues under the Income-tax Act, 2025. The Tribunal can condone delay for sufficient cause.
- Can the ITAT stay a tax demand?
- Yes. The Tribunal can stay recovery of a disputed demand while an appeal is pending, usually on deposit of a part of the demand or furnishing security. Stays are granted for a limited period, and the appeal is expected to be decided within it.
- Where does an appeal go after the ITAT?
- An appeal against an ITAT order lies to the High Court, but only on a substantial question of law. A further appeal lies to the Supreme Court.
- How can White Collar Professional help with a ITAT matter?
- Post your requirement on White Collar Professional to receive proposals from verified Chartered Accountants and tax Advocates, compare them, and pay securely through the platform. This page also tracks the latest ITAT ITAT orders as they are reported.









