ITAT Mumbai: Entire Receipts Cannot Be Taxed as Unexplained Income; Adhoc Disallowance Upheld for Unverified Expenses in SRA Consultancy Case
Court / Authority
Income Tax Tribunal
Update / Judgement Date
18 Aug 2026
Source
WCP News Bulletin
Author
Manas Yadav — WCP Legal Desk
Reading Time
2 min read
View Count
3
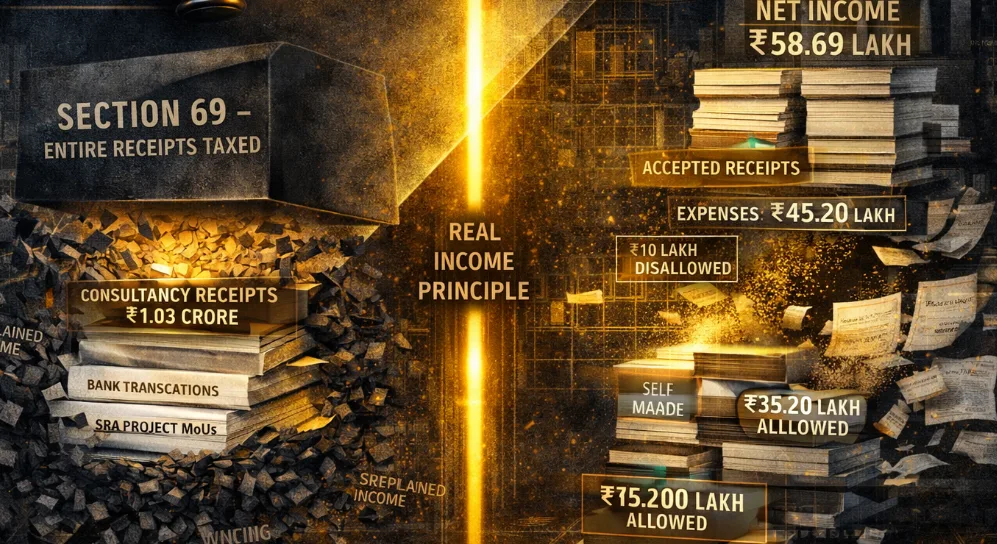
Key Facts and Tribunal Findings
The Mumbai ITAT examined the taxability of consultancy receipts and related expense claims in the case of an individual assessee engaged in a one-time liaisoning activity for Slum Rehabilitation Authority (SRA) redevelopment projects. The assessee had earned consultancy receipts aggregating ₹1.03 crore from multiple redevelopment projects and declared net income of ₹58.69 lakh after claiming expenses of ₹45.20 lakh. However, the Assessing Officer treated the entire gross receipts as unexplained investment under Section 69 and disallowed the entire expense claim, citing lack of supporting evidence.
The CIT(A) upheld the assessment, rejecting additional evidences such as Memoranda of Understanding (MoUs), vouchers, and ledger extracts on the ground that these were not produced during assessment proceedings and did not satisfy the conditions under Rule 46A. On appeal, the ITAT found that the existence of the underlying activity and receipt of income could not be disputed. The Tribunal noted that the assessee had furnished MoUs with project coordinators and that part of the receipts had been routed through banking channels, lending credibility to the transactions. Accordingly, it held that the Assessing Officer’s action of treating the entire receipts as unexplained income was unsustainable. However, on the issue of expenses, the Tribunal agreed that the assessee failed to substantiate the claim with reliable evidence at the assessment stage. The reliance on self-made vouchers and late production of documents weakened the claim. Taking note of the assessee’s concession, the ITAT upheld an ad hoc disallowance of ₹10 lakh and directed deletion of the balance ₹35.20 lakh.
Legal Analysis and Practical Implications
The ruling draws a clear distinction between the existence of income-generating activity and the substantiation of expenditure. The Tribunal reaffirmed that where receipts are acknowledged and partially supported by documentation and banking trails, taxing the entire gross amount as unexplained under Section 69 is not justified. At the same time, the decision underscores the evidentiary burden on taxpayers to substantiate expense claims. The rejection of additional evidence under Rule 46A highlights the procedural importance of presenting complete documentation during assessment proceedings. Self-generated vouchers, without corroboration, are insufficient to support substantial deductions.
The Tribunal’s acceptance of a reasonable ad hoc disallowance reflects a pragmatic approach, balancing the absence of full documentation with the commercial reality of expenditure in such transactions.
Full Judgement / Attachment
Full Judgement
Frequently asked questions about Income Tax Tribunal
- What is the Income Tax Appellate Tribunal (ITAT)?
- The ITAT, set up in 1941, is the second appellate authority in direct tax matters and the final fact-finding body. It hears appeals against orders of the Commissioner (Appeals) and certain other authorities, through benches across India.
- What is the time limit to file an appeal before the ITAT?
- An appeal must be filed within two months from the end of the month in which the order is communicated. This rule has applied since 1 October 2024 and continues under the Income-tax Act, 2025. The Tribunal can condone delay for sufficient cause.
- Can the ITAT stay a tax demand?
- Yes. The Tribunal can stay recovery of a disputed demand while an appeal is pending, usually on deposit of a part of the demand or furnishing security. Stays are granted for a limited period, and the appeal is expected to be decided within it.
- Where does an appeal go after the ITAT?
- An appeal against an ITAT order lies to the High Court, but only on a substantial question of law. A further appeal lies to the Supreme Court.
- How can White Collar Professional help with a ITAT matter?
- Post your requirement on White Collar Professional to receive proposals from verified Chartered Accountants and tax Advocates, compare them, and pay securely through the platform. This page also tracks the latest ITAT ITAT orders as they are reported.









