ITAT Mumbai Recognises Allotment Date for Stamp Duty Valuation in Property Purchase Case
Court / Authority
Income Tax Tribunal
Update / Judgement Date
17 Jul 2026
Source
WCP News Bulletin
Author
Manas Yadav — WCP Legal Desk
Reading Time
2 min read
View Count
5
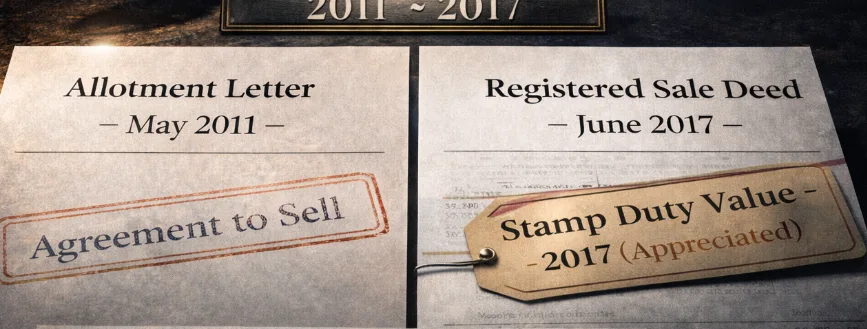
Allotment Letter Held Relevant for Section 56(2)(x) Computation
The Mumbai Bench of the Income Tax Appellate Tribunal granted substantive relief to Ms. Cherie Tandon Saldahna in a dispute arising from addition made under Section 56(2)(x) of the Income Tax Act for Assessment Year 2018–19. The Assessing Officer had treated the difference between the purchase price of a residential flat and its stamp duty valuation as taxable income from other sources, resulting in an addition of approximately ₹1.14 crore. The valuation was taken as on the date of registration in June 2017, when the stamp duty value had significantly appreciated. The assessee contended that the property was originally allotted in May 2011 through a formal allotment letter, and the entire consideration had been paid through banking channels long before execution of the sale deed. It was argued that in view of the provisos to Section 56(2)(x), the stamp duty value applicable on the date of agreement should govern the tax computation where consideration is paid prior to registration.
Tribunal Restores Matter for Verification and Grants Relief
Accepting the legal position advanced by the assessee, the Tribunal held that the allotment letter constituted a valid agreement to sell for the purposes of Section 56(2)(x). It observed that where payment conditions prescribed under the provisos are satisfied, the relevant stamp duty value must be taken as on the date of allotment and not the date of registration.
Accordingly, the matter was remanded to the Assessing Officer for limited verification of payment details, with directions to recompute the addition by applying the stamp duty value prevailing in May 2011. The appeal was thus allowed for statistical purposes, reaffirming the importance of agreement dates in property taxation disputes.
Full Judgement / Attachment
Full Judgement
Frequently asked questions about Income Tax Tribunal
- What is the Income Tax Appellate Tribunal (ITAT)?
- The ITAT, set up in 1941, is the second appellate authority in direct tax matters and the final fact-finding body. It hears appeals against orders of the Commissioner (Appeals) and certain other authorities, through benches across India.
- What is the time limit to file an appeal before the ITAT?
- An appeal must be filed within two months from the end of the month in which the order is communicated. This rule has applied since 1 October 2024 and continues under the Income-tax Act, 2025. The Tribunal can condone delay for sufficient cause.
- Can the ITAT stay a tax demand?
- Yes. The Tribunal can stay recovery of a disputed demand while an appeal is pending, usually on deposit of a part of the demand or furnishing security. Stays are granted for a limited period, and the appeal is expected to be decided within it.
- Where does an appeal go after the ITAT?
- An appeal against an ITAT order lies to the High Court, but only on a substantial question of law. A further appeal lies to the Supreme Court.
- How can White Collar Professional help with a ITAT matter?
- Post your requirement on White Collar Professional to receive proposals from verified Chartered Accountants and tax Advocates, compare them, and pay securely through the platform. This page also tracks the latest ITAT ITAT orders as they are reported.









