ITAT Remands Section 270A Penalty Over Form-26AS Revenue Mismatch
Court / Authority
Income Tax Tribunal
Update / Judgement Date
03 Jul 2026
Source
WCP News Bulletin
Author
Manas Yadav — WCP Legal Desk
Reading Time
2 min read
Background
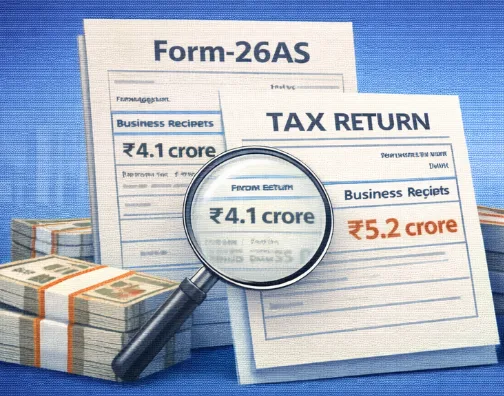
The Mumbai “D” Bench of the Income Tax Appellate Tribunal set aside the penalty of ₹46.87 lakh imposed on Mark Engineers (India) Pvt. Ltd. for alleged under-reporting of income for AY 2018–19. The penalty arose after the Assessing Officer treated the difference between business receipts reflected in Form-26AS and those reported in the return as undisclosed income, along with minor disallowances under Sections 40(a)(i) and 36(1)(va). Since the assessee did not challenge the quantum addition, penalty proceedings under Section 270A were initiated and sustained by the CIT(A).
Recovery of Old Debtors Claim Requires Verification, Says Tribunal
Before the ITAT, the assessee explained that the Form-26AS figures represented recovery of earlier years’ sundry debtors on which TDS was deducted at the time of payment, while revenue had already been offered on accrual basis in prior years. The Tribunal reiterated that quantum and penalty proceedings are independent and noted that the CIT(A) failed to verify this reconciliation explanation. Since the issue required factual examination of past revenues and debtor balances, the matter was remanded to the Assessing Officer for fresh verification. The appeal was allowed for statistical purposes, with directions for proper opportunity of hearing.
Full Judgement / Attachment
Full Judgement









