NCLT Ahmedabad directs meetings on Essar Power–Abhinand Ventures demerger and capital reduction scheme
Court / Authority
Income Tax Tribunal
Update / Judgement Date
28 Jun 2026
Source
WCP News Bulletin
Author
Manas Yadav — WCP Legal Desk
Reading Time
2 min read
View Count
1
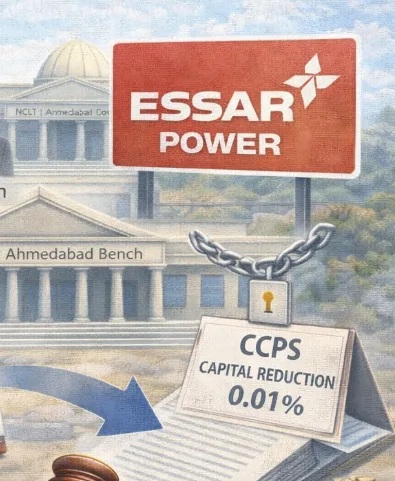
NCLT admits scheme involving brand demerger and CCPS capital reduction
The Ahmedabad Bench of the National Company Law Tribunal has admitted a joint company application filed by Abhinand Ventures Private Limited and Essar Power Limited under Sections 230 to 232 read with Section 66 of the Companies Act, 2013, seeking directions in relation to a composite scheme of arrangement. The Division Bench comprising Judicial Member Shammi Khan and Technical Member Sanjeev Sharma passed the order on January 28, 2026.
The proposed scheme provides for the demerger of the ‘Brand Undertaking’ of Abhinand Ventures into Essar Power on a going concern basis, along with reduction of Essar Power’s 0.01% compulsorily convertible cumulative preference shares (CCPS) and reorganisation of its reserves. The Tribunal accepted the appointed date of April 1, 2025, holding that a retrospective date aligned with the financial year did not prejudice stakeholders and was permissible under Section 232(6). It was also noted that no insolvency proceedings were pending against either company.
Meetings directed; some classes granted dispensation
After examining the shareholding and creditor structure, the NCLT dispensed with meetings of equity shareholders and optionally convertible debenture holders of Abhinand Ventures, as well as preference shareholders of Essar Power, in view of written consents placed on record. However, the Tribunal directed that meetings of non-convertible debenture holders and unsecured creditors of Abhinand Ventures, and meetings of equity shareholders, non-convertible debenture holders, and unsecured creditors of Essar Power, be convened on March 14, 2026, either physically or through video conferencing.
The Bench appointed an advocate as chairperson and a company secretary as scrutiniser to oversee the meetings and directed statutory notices and advertisements in accordance with the Companies (Compromises, Arrangements and Amalgamations) Rules, 2016. Regulatory authorities including the Registrar of Companies, Regional Director and Income Tax Department were also directed to be notified under Section 230(5). The application was accordingly allowed, paving the way for stakeholder consideration of the scheme.
Full Judgement / Attachment
Full Judgement
Frequently asked questions about Income Tax Tribunal
- What is the Income Tax Appellate Tribunal (ITAT)?
- The ITAT, set up in 1941, is the second appellate authority in direct tax matters and the final fact-finding body. It hears appeals against orders of the Commissioner (Appeals) and certain other authorities, through benches across India.
- What is the time limit to file an appeal before the ITAT?
- An appeal must be filed within two months from the end of the month in which the order is communicated. This rule has applied since 1 October 2024 and continues under the Income-tax Act, 2025. The Tribunal can condone delay for sufficient cause.
- Can the ITAT stay a tax demand?
- Yes. The Tribunal can stay recovery of a disputed demand while an appeal is pending, usually on deposit of a part of the demand or furnishing security. Stays are granted for a limited period, and the appeal is expected to be decided within it.
- Where does an appeal go after the ITAT?
- An appeal against an ITAT order lies to the High Court, but only on a substantial question of law. A further appeal lies to the Supreme Court.
- How can White Collar Professional help with a ITAT matter?
- Post your requirement on White Collar Professional to receive proposals from verified Chartered Accountants and tax Advocates, compare them, and pay securely through the platform. This page also tracks the latest ITAT ITAT orders as they are reported.









